On September 24, according to China Business News, the average price of beef in the national agricultural wholesale market has rebounded to its highest point in more than two years.
Monitoring data from the Ministry of Agriculture and Rural Affairs show that the average price of beef in the national agricultural wholesale market on September 21 was 71.59 yuan/kg, an increase of nearly 6% since the beginning of August and an increase of nearly 9% from a year ago. In the 38th week (September 14th to 20th), the weekly average price of beef wholesale market was 71.08 yuan per kilogram, an increase of 1.3% month-on-month and 8.4% higher than the same period last year.
On the evening of September 24, the customer service of an online steak store told Jiemian News: “Domestic beef raw material prices continue to rise this year. Beef ribs are affected by market conditions, and we have no choice but to fine-tune the price again.”
It is understood that the primary reason for this round of beef price increases is supply contraction. Data from the National Bureau of Statistics show that the national cattle population dropped to 96.08 million heads at the end of 2025, and further fell to 95.57 million heads by the end of the second quarter of 2026, a year-on-year decrease of 4.3%. CITIC Futures data shows that the industry has experienced continuous losses for about three years from 2023 to 2025, and the cumulative number of breeding cows has been reduced by 15% to 20%, with some core production areas exceeding 30%.
In addition to reduced domestic supply, a contraction in imported beef is exacerbating tight supply and demand. On December 31, 2025, the Ministry of Commerce issued an announcement and decided to take safeguard measures on imported beef in the form of “country-specific quotas and additional tariffs in addition to quotas.” The measures will be implemented from January 1, 2026 for a period of three years. Imported beef that exceeds the quota will be levied an additional 55% on the current applicable tariff rate. The case involved a total amount of approximately US$13.7 billion, making it China’s largest trade remedy investigation case to date.
The supply side is shrinking, and the demand side has entered the traditional peak season. The fourth quarter is the peak season for beef consumption. The Mid-Autumn Festival and National Day are approaching, and holiday banquets, family reunions, and beef gift box purchases are all launched. The drop in temperature after autumn also drives the consumption of catering such as family stew and beef hot pot. Zhuochuang Information analyst Shao Qiankan believes that demand during peak consumption seasons usually increases by about 5%, and beef prices are expected to remain high.
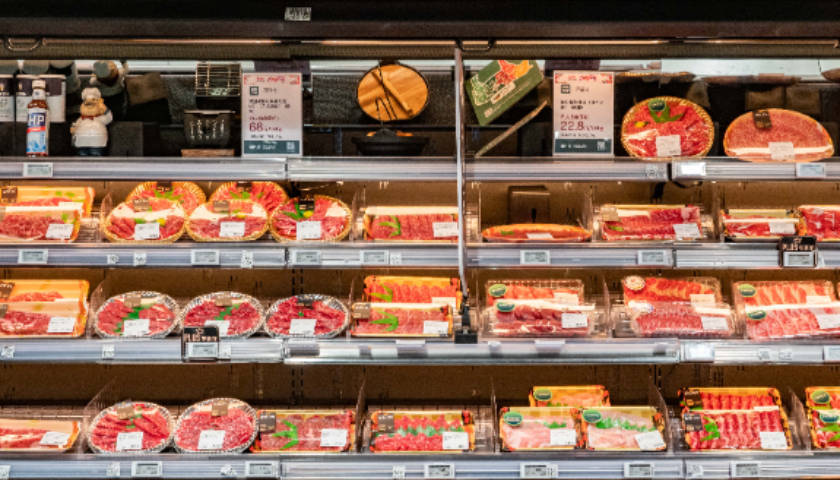
According to Hunan Daily, regarding the subsequent trend of beef prices, industry insiders believe that in the short term, with the peak of holiday consumption, the beef market demand will continue to be strong, prices are likely to remain high, and the trend of slight fluctuations and increases will continue. In the medium and long term, the beef cattle breeding cycle is long, the recovery rate of the stock is slow, and the supply is difficult to increase significantly in the short term. It is expected that the overall beef price will be in a high range in the fourth quarter, and it is difficult to fall significantly.
Brett Stuart, a senior analyst at Global AgriTrends, an international agricultural consulting organization, issued a judgment at an industry conference that global beef supply will enter a continued downward cycle from 2027 to 2028. The tight supply and demand pattern will provide solid support for international beef prices. For the first time, the world’s major beef producing countries have simultaneously launched a cattle de-stalling cycle. The global beef structural high price cycle will continue until at least 2028, and the price bottom of this cycle will be significantly higher than the same period in history.
A relevant research report from Industrial Securities pointed out that the self-sufficiency gap is expected to continue to expand from 2026 to 2027; this upward cycle is based on three supports – the stock of fertile cows is at a historical low (it will take at least 3 years for supply to recover), import safeguard measures from 2026 to 2028 limit the impact of low-price imports, and global cattle prices start to rise before China.
Not all institutions are bullish. Agricultural data agency Nongxiaofeng predicts in the “2026 China Beef Cattle Industry Data Analysis Report” that in 2026 due to the combined effects of multiple factors such as low breeding cow numbers and rising production costs, the prices of feeder cattle and beef are expected to rebound further, but the weak recovery of end consumption will restrict the room for increases in live cattle and beef prices.
Related Reading
- Original: 4 teachers guard 9 primary school students, they can’t just calculate economic accounts2026-09-25
- The first provincial capital in the north is not “strong” enough?2026-09-25
- How much passenger traffic does high-speed rail take away from airplanes? 10%2026-09-25
- The pit of the 10 trillion world copper king is deeper than Evergrande2026-09-24
- From the start of a business to sailing overseas, the “two-way rush” between China Minsheng Bank and specialized new enterprises2026-09-24