After taking the lead in scale, the most difficult problem for Chinese automobiles is profitability
1.9萬
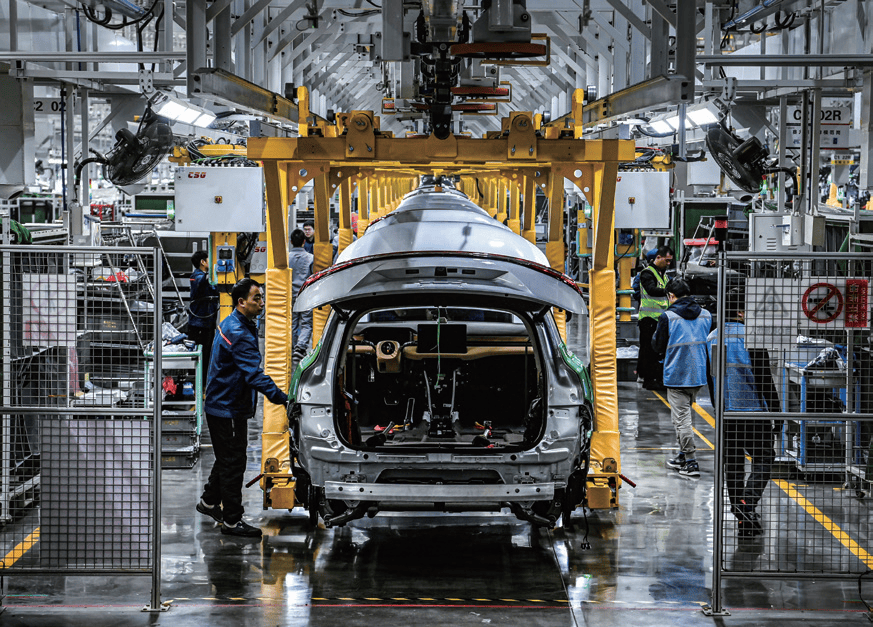
After taking the lead in scale, the “15th Five-Year Plan” of nine ministries and commissions has shifted the yardstick of automobile power from sales volume to system capabilities. The industry has entered into in-depth adjustment and pattern reshaping amidst the test of low profitability, intelligence and globalization.
文|“Finance” special writers Wang Xin Song Liwei
編輯|趙成
2026 is the opening year of the grand blueprint of the “15th Five-Year Plan”, and it is also a critical step for China’s automobile industry to move forward into the deep-water zone of high-quality development. Improving quality and efficiency, and ecological integration and innovation will become an important cornerstone for the transformation and upgrading of the automobile industry and high-quality development.
On September 11, nine ministries and commissions including the Ministry of Industry and Information Technology and the Ministry of Public Security jointly released the “15th Five-Year Plan for the Development of the Intelligent Connected New Energy Vehicle Industry” (hereinafter referred to as the “Plan”), which is regarded as a key top-level design for the automotive industry to enter the ranks of the world’s automotive powers.
The “Plan” clearly states that by 2030, domestic new energy passenger vehicles and commercial vehicles will account for 70% and 40% respectively of the total sales of new vehicles in their respective fields, and vehicles with autonomous driving functions will be applied on a large scale. Further improve key technologies, industrial structure, international development, social and economic benefits, etc., and cultivate several complete vehicle companies that have entered the top ten in global sales and the world’s top 100 parts companies.
Looking back on the “14th Five-Year Plan”, the market size of the new energy vehicle industry has jumped from one million to ten million, and technologies such as vehicle integration, power batteries, smart cockpits, and laser radar have entered the forefront of the world. The production and sales of new energy vehicles have ranked first in the world for 11 consecutive years. From January to August 2026, the penetration rate rose to 52.4%. From January to July, vehicle exports were 6.41 million units, a year-on-year increase of 54%.
On this basis, the “15th Five-Year Plan” will initiate a critical transformation of the automobile industry from scale expansion to quality improvement. Luo Junjie, vice president of the China Machinery Industry Federation, pointed out at the 22nd China Automotive Industry Development (TEDA) International Forum (hereinafter referred to as the “TEDA Automobile Forum”) that the “Plan” has sounded the clarion call for China to enter the ranks of the world’s automotive powers. Domestic automotive technology and equipment have got rid of the passive situation of simply following and entering a new stage of running alongside and partially leading.
與What contrasts the policy setting is the pressure of industrial reality. In the first half of 2026, the average profit margin of automobile manufacturing companies dropped to a nearly decade low of 1.5%, and 8 of the 15 listed automobile companies suffered losses. The involution and price war have not stopped, and 70% of the vehicles on sale only sell a few thousand units per year. Going overseas encounters EU localization procurement, tariffs and technology transfer thresholds on the order of tens of millions of vehicles. The circulation link is newThe gross profit margin of vehicles is negative, and the dealer profit model is unsustainable.
The direction has been pointed out, but as for the next step, the market is looking forward to first-line action.
Planning sets quantitative coordinates, and the competitive benchmark turns to system capabilities
Wang Weiming, chief engineer of the Ministry of Industry and Information Technology, pointed out at this TEDA Forum that the “Plan” promotes the industry from leading in scale to leading in quality and system.
The “Plan” sets a target system in a “1+4” structure for the first time. The overall goal is to further consolidate the advantages of the entire industry chain and enter the ranks of the world’s automotive powers by 2030.
Among the four sub-goals, the key technical level requires the average fuel consumption of passenger cars to be reduced to 3.3 liters per 100 kilometers, the average electric energy consumption of pure electric passenger cars to be reduced to about 11.5 kilowatt-hours per 100 kilometers, and scenes such as highways and urban expressways to achieve highly autonomous driving; in terms of industrial structure, the labor productivity of all employees is required to increase by 15% compared with 2025, and to cultivate several vehicle companies that enter the top ten in global sales and the world’s top 100 parts companies.
In terms of international development, the “Plan” requires Chinese automobile brands to have a high reputation and further enhance their voice in international standards and regulations; economic and social benefits require that carbon dioxide peaks before 2030, and the safety performance of vehicles equipped with autonomous driving systems significantly exceeds that of human drivers.
At the task level, the “Plan” deploys five major tasks to improve technological innovation capabilities, promote optimization and upgrading of industrial systems, promote cross-border integrated development, build a scientific and efficient industry governance system, and create a new situation for global industrial cooperation, including key technology research, artificial intelligence vehicles, ecological construction of key parts and components, application promotion, standards and testing and evaluation, safety foundation building, and international capability improvement.
Unlike the “14th Five-Year Plan” which focuses on electrification and scale, the “Plan” puts intelligence, governance standardization and global cooperation in an equally important position. For the first time, industry governance provisions cover issues such as production capacity early warning and regulation, anti-monopoly and anti-unfair competition law enforcement, and cross-border data flow.
How the industry achieves the above goals depends on the judgments at the ministry level and within the industry.
At the strategic level, Wang Weiming said that the automobile industry is a strategic pillar industry of the national economy and an important carrier for the centralized application of a new round of technological revolution and industrial transformation. The next step will focus on strengthening technological innovation, expanding market consumption, optimizing industry management, and deepening openness and cooperation to implement comprehensive policies.
Luo Junjie reminded that whether a country becomes strong cannot only depend on the scale of the industry, but also on quality, efficiency and core competitiveness of the enterprise. The industry is at a critical juncture from scale leadership to quality leadership, and from product advantages to system advantages. High-quality automobile products must not only rely on R&D and design to define the product upper limit, but also rely on advanced technology and equipment to build a solid quality bottom line.
“The core competitiveness of the automobile industry is ultimately the competitiveness of the manufacturing system and equipment ecology.” Luo Junjie said.
On September 15, at the media conference of the Auto Baihui Annual Meeting and Intelligent Electric Vehicle Development High-Level Forum (2027), Zhang Yongwei, chairman of the Auto Baihui Research Institute, told Caijing that the plan has completed the coordinate transformation from a major automobile country to a powerful automobile country, and the kinetic energy has switched from fuel vehicles to electrification, intelligence, and globalization. This structure has been formed and irreversible. In contrast, Europe is still stuck on the old kinetic energy, “wanting to be fast but unable to get up fast.”
The confidence of the “Plan” comes from the overall jump in China’s manufacturing industry. Tian Jietang, director of the Industrial Economic Research Department of the Development Research Center of the State Council, pointed out that China’s manufacturing share of the global manufacturing industry has increased from about 10% to 27%. The number of artificial intelligence companies in the manufacturing field ranks among the top in the world. Automobiles are the core carrier for artificial intelligence to move from the digital world to the physical world.
Many experts believe that the 70% and 40% ratio targets are conservative. Dong Yang, chairman of the China Automotive Power Battery Industry Innovation Alliance, further pointed out that this is likely to be an intentional design to prevent the industry from blindly rising. He said, “Planning no longer puts development speed first, and the industry should abandon the idea of barbaric development and excessive pursuit of disruptive development.”
Stabilizing the market in the low profit range has become a core proposition
“There are still some problems and challenges that cannot be ignored in the current industrial development, including shortcomings in high-end process chips and operating systems, competition in new technologies such as new generation power batteries and autonomous driving has become increasingly fierce, domestic consumer demand is insufficient, and the profit margin of the automobile manufacturing industry continues to decline.” Wang Weiming pointed out.
The average profit margin of automobile manufacturing companies in the first half of 2026 was 1.5%, falling to the lowest point in the past decade.
Based on this, the market’s first judgment is stability.
Zhang Yongwei told Caijing that the industry will usher in a downward adjustment in 2026, but the magnitude will not exceed 2025. The industry has entered a stage of development focused on stability, and it will be difficult to reproduce the rapid growth after 2009; 35 million vehicles is the scale that the industry can expect, and 35 million to 40 million vehicles is a more ideal range. Excessive growth may not be good for the industry, and sudden rises and falls are not healthy.
Behind stability is profitability. The current market is characterized by strong supply and weak demand. 70% of so-called new cars only sell a few thousand units a year. The main contradiction between the large variety and the insufficient scale of bicycles. Zhang Yongwei estimates that automobile consumption accounts for about 10% of the total retail sales of consumer goods. Every reduction in domestic demand by 1 million units will drag down national domestic demand by about 0.35 percentage points. Domestic demand of 25 million units is the basic market that must be defended.
The changes in the industry’s internal structure have appeared on the circulation side. Data provided by Wang Du, vice president of the China Automobile Dealers Association, show that the average gross profit margin of new cars is negative 21.4%, the industry’s average inventory cycle is 1.58 months, and dealers’ satisfaction with OEMs dropped to 56.3%, the lowest in recent years. After-sales and financial insurance gross profits can no longer support the service system, and circulation is shifting from the end of the industry to the end of value input.
“Anti-involution” has become an explicit issue at the governance level.
Dong Yang suggested that the government should focus on restraining entities that engage in excessive involution, and can use methods such as subjective evaluation of actual vehicle performance and back-to-back surveys of multiple vehicle companies to identify involution behaviors.
In this regard, Liu Zongcheng, president of Cyrus Group Technology Company, proposed to form industry self-discipline to curb malicious low prices, data falsification, and black public relations.
“The biggest risk in the automobile industry is not slowness but quick success. You can’t get far by relying on quick success, and you can’t win the future by relying on low prices. There are no bystanders in integration, and only collaboration can win the future; competition determines how fast we can run, and symbiosis determines how far we can go.” Liu Zongcheng said.
“Anti-involution” also extends to technical lines. Dong Yang reminded that the industry has entered a technology no-man’s land. The past era of following overseas paths is over. Research on basic and common technologies must be promoted independently, but the specific direction should be determined by the company based on actual product development, and it is important to avoid blindly following trends. He took solid-state batteries as an example. The phenomenon of following trends in the industry is quite prominent. There are many directions worthy of research in the battery field, and they are not limited to solid-state batteries.
At the policy level, the “Plan” proposes to strengthen anti-monopoly, anti-unfair competition and price law enforcement and justice, and regulate local improper investment promotion behaviors such as illegal provision of financial subsidies and tax concessions. The era of relying on increments to cover up problems is over, and elimination, stratification, and clearing within the industry are accelerating.
The era of AI cockpit is coming, L4 is speeding up
The strategic path for intelligentization will be set first at the ministry level.
Wang Weiming said that we will actively and steadily promote the access and on-road pilot projects for intelligent connected vehicles, improve the access management requirements for combined driving assistance and autonomous driving systems, and always put safety first.
In terms of industrial base, Luo Junjie believes that the new generation of smart manufacturing empowered by artificial intelligence is the main direction. Technologies such as AI (artificial intelligence) adaptive control, digital twin simulation, and intelligent operation and maintenance monitoring will support flexible production of multiple models, automatic process optimization, and intelligent defect detection.
Rhythm judgments are equally focused.
Zhang Yongwei told Caijing that the industry will enter the AI cockpit era in 2027, which will be marked by the mass production of large-scale AI cockpit products. The cockpit will shift from calling apps to intelligent assistants with interaction and companionship capabilities. From 2027 to 2028, artificial intelligence and the entire automotive industry will Chain integration will be one of the core themes; the core competitiveness of intelligent driving is concentrated in large models and vehicle-mounted chips. The industry’s single-chip computing power has entered the 1000TOPS (trillion operations per second) era, and the integration of cabin and driving has driven computing power demand to the 2000TOPS level.
At the L4 level, the four tracks of self-driving taxis, high-speed trunk logistics, closed scenes in port and mining areas, and functional unmanned vehicles will be accelerated. Among them, functional unmanned vehicles have clarified their special intelligent equipment attributes due to the new version of the Road Traffic Safety Law, and the market volume is expected to move from tens of thousands to hundreds of thousands.
However, institutional and technological rhythms are variables. The revision of the Road Traffic Safety Law is a prerequisite for the scale of L3 and L4. Wang Chao, president of Huawei’s digital energy smart electric product line, believes that 2027 may be the basic year of L3 and 2028 the basic year of L4. Underlying innovation in the sports domain is the path to breaking homogeneity.
However, AI intelligence poses higher-level risks in the competitive landscape.
According to Mei Guanqun, director of the Innovation and Development Research Department of the China Center for International Economic Exchanges, the integration of artificial intelligence and transportation is the first step in the artificial intelligence game between China and the United States. China has the world’s largest transportation scenarios and data resources, but the scenario advantages have not yet been fully transformed into data and standard advantages.
“The U.S. Department of Transportation has released a national strategy for autonomous driving from 2026 to 2030. Tesla’s cumulative driving mileage has exceeded 10 billion miles, and Waymo’s test fleet has exceeded 4,000 vehicles. The United States is advancing by deploying, supervising, and revising rules. Once the American model becomes the basic operating system in the era of physical artificial intelligence, China’s autonomous driving, robotics and other industries will be controlled by others.” Mei Guanqun said.
But domestic car companies are already taking action. Zhang Xiaoyu, executive vice president of Changan Automobile, said that after Changan Automobile and BAIC jointly obtained the country’s first batch of L3 autonomous driving product access licenses, they released the Tianshu large model in September, with a cumulative intelligent user mileage of 1.539 billion kilometers.
Zhang Xiaoyu believes that the industry is accelerating from factor-driven to innovation-driven, building self-evolving vehicles with intelligence as the core, building full-area linkage protection with safety as the bottom line, opening up four-chain collaboration with ecology as the growth pole, and jointly building a new pattern of smart and green symbiotic industries.
Therefore, intelligence is the main track of certainty, but the closed loop of commercialization, institutional support and global rules competition determine the speed of its realization.
After 10 million vehicles shipped overseas, localization game and pattern reshaping
Internationalization is placed in the “Plan” to create a new situation in global industrial cooperation.
Wang Weiming said that we should adhere to international innovation and global development, oppose all forms of protectionism, promote mutual recognition of international standards and rules, support Chinese and foreign enterprises in joint technological research, and improve the automobile export guarantee system.
The larger the magnitude, the clearer the hidden concern.
Zhang Yongwei judged that domestic automobile exports are expected to reach 10 million units this year, and may even reach 15 million units. However, it is difficult for the external market to accept such a large-scale vehicle import, and a large number of vehicles sold overseas are out of warranty. Localization is the most prominent problem at the moment. If the draft EU-related industrial bill is implemented, the local procurement ratio of Chinese car companies may increase from the current 30% to 60%, and technology license transfer will be mandatory.
“We cannot simply conduct overseas business based on the mentality of trade games and compliance confrontation. The more the industry develops and progresses, the more we must insist on opening up.” Dong Yang said.
The narrative of companies going overseas is shifting from product output to system output. It is reported that Great Wall Motors divides its overseas expansion into three stages: hardware overseas expansion, technology overseas expansion, and ecological overseas expansion. It is currently entering the ecological overseas expansion stage.
“Intelligence has become the most distinctive label and differentiated competitive advantage for Chinese cars going overseas. This means that Chinese car companies cannot rely solely on price-performance when going overseas, nor can they only carry out shallow technology adaptation. Instead, they must build intelligence into a systematic and reusable core overseas capability to support long-term competition in overseas markets.” said Chen Xiaofeng, vice president and chief scientist of Great Wall Motor Technology Center.
Parallel to going overseas, the domestic landscape is being reshaped. The “Plan” proposes for the first time early warning and regulation of production capacity, intensifies mergers and reorganizations and cross-regional integration of enterprises in accordance with the law, and promotes the orderly exit of backward and inefficient production capacity through market-based and legal methods.
Zhang Yongwei told Caijing that industry mergers and reorganizations will become a normal trend in the next few years, market-oriented mergers and reorganizations should become the mainstream, and the government should not forcefully match resources. The global narrative of Chinese automobiles is shifting from product output to technology, standards and lifestyle output. The reshaping of the domestic landscape will find a balance between market clearing and policy support.
Planning gives coordinates, experts give paths, and enterprises give practices. The period of in-depth adjustment is also a period of pattern reshaping. Only companies that can find a balance between survival and investment in the low-profit range, establish localized systems in the wave of overseas expansion, and clear the business closed loop in intelligent investment can occupy a place on the coordinates of the automotive power in 2030. Who can arrive first, the market will give the answer.
Return to the homepage to see more car information
Related Reading
- Hiking becomes popular during the National Day, with young people escaping from their workplaces spending tens of thousands of yuan to hike into the mountains2026-10-04
- After falling by more than 80% in 5 years, Nike has completely fallen from the altar.2026-10-04
- Original fine of 9.75 million! The day before the holiday, Hangzhou Bank was “heavily hammered” by supervision2026-10-04
- After not filming for more than 600 days, how did Zhao Lusi make more money?2026-10-04
- Original 600 billion wiped out in ashes! Arowana disguised as a domestic product, how could the former “king” decline?2026-10-03