From boom to ebb, why does U.S. battery investment fluctuate?
9230
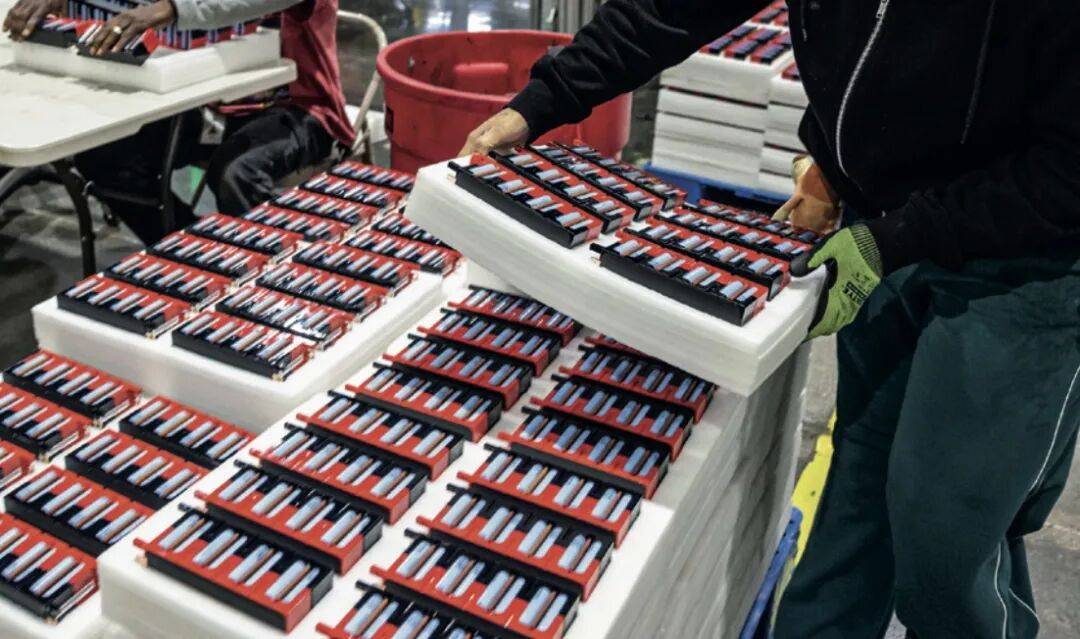
Subsidies have declined and demand has cooled, causing the battery investment boom in the United States to subside. Existing factories are suffering from declining utilization rates and switching technology routes.
Text | “Finance” Chief Writer Yin Lu
Editor|Cathy Huang
The U.S. battery manufacturing industry is digesting the production lines formed in the last round of expansion and adjusting subsequent plant construction plans. At the same time, amidst the differences in growth trends between the electric vehicle and energy storage markets, battery products and technical routes must be re-selected.
In the past few years, the electrification plans of U.S. car companies, federal tax credits and state investment incentives have jointly promoted a wave of investment in battery factories. These projects extend from the traditional automotive industry hinterland in the Midwest such as Michigan and Ohio to southern manufacturing bases such as Kentucky, Tennessee, Georgia, and North and South Carolina, forming the “battery belt” of the United States.
In August 2022, the Inflation Reduction Act (IRA) promoted by the Biden administration was implemented to support electric vehicle consumption and the construction of electric vehicle and battery production capacity through car purchase tax credits and local manufacturing incentives. After the Trump administration came to power in 2025, clean energy-related policies shifted rapidly, the car purchase tax credit was terminated early, and electric vehicle sales fell accordingly. Car companies have reduced the production lines of pure electric models, and battery companies have also adjusted their investment plans.
According to statistics from the American think tank Atlas, the total investment in new electric vehicles and supply chains in the United States has plummeted from a peak of approximately US$55 billion in 2023 to approximately US$6.5 billion in 2025. In 2025 alone, the originally canceled investment commitments for electric vehicle-related projects were nearly US$20 billion. From the beginning of 2025 to August 2026, the canceled projects involved a total of approximately 27,000 committed positions.
At a time when overall investment is shrinking, established battery factories are still facing product route choices: demand for electric vehicles has slowed, and the energy storage market has grown significantly, attracting companies to switch production and looking for short-term orders to absorb idle production capacity; the next generation of electric vehicles requires low-cost, high-energy-density batteries, which in turn affects subsequent technology investment.
The adjustment of Ultium Cells, the new energy joint venture between General Motors and LG, is the most typical. Its factory in Spring Hill, Tennessee, was first used to support GM’s electric vehicles and has a planned power battery production capacity of over 45GWh (gigawatt hours). In June 2026, it completed a US$70 million transformation and switched to the production of soft-packed lithium iron phosphate (LFP) cells for energy storage systems (ESS).
Three months later, GM announced at the end of September that it would increase the production capacity of lithium-rich manganese-based (LMR) prismatic battery cells for next-generation electric vehicles at the plant. Relevant facility renovation is expected to start in 2026 and be completed in 2028, adding about 500 new jobs. The factory’s product portfolio covers both energy storage and automotive applications.
GM said that the design energy density of lithium-rich manganese-based batteries is 33% higher than that of lithium iron phosphate, and the manufacturing cost is similar. Ultium Cells is expected to become the world’s first company to commercially mass-produce LMR square batteries.
This swing reflects the current situation of the U.S. battery manufacturing industry: end-use electric vehicle demand is lower than expected, forcing factories to convert to energy storage to save themselves; OEMs still have to bite the bullet and continue to invest in new technology routes in order to overcome cost bottlenecks and maintain mid- to long-term competitiveness.
Policy changes, investment ebbs
The explosive expansion of the U.S. “battery belt” was spurred by federal bills, state government investment, and radical transformation of traditional car companies: U.S. auto giants are eager to reconstruct local supply chains, Japanese and Korean and other Asian battery companies need to be close to North American vehicle customers, and state governments in the Midwest and South are eager to use new energy bases to replace manufacturing jobs lost to fuel vehicles.
The wave of battery factory construction has started between 2019 and 2022. According to public information statistics, half of the 52 major battery projects in the United States were sited or invested before the implementation of the IRA in August 2022.
The IRA has injected a boost into both supply and demand sides of the craze: on the supply side, qualified locally made cells can receive an advanced manufacturing tax credit of up to US$35/kWh, and module manufacturing can enjoy an additional US$10/kWh credit. On the demand side, new energy vehicles that meet the thresholds for North American assembly and localization of critical minerals and battery components can enjoy a federal vehicle purchase tax credit of up to $7,500. Coupled with low-priced land, infrastructure expansion and labor subsidies in various states, automobile and battery companies’ expectations for future electric vehicle shipments have been pushed to the top.
Investment expectations will immediately shift in 2025 with the coming of the Trump administration. In July 2025, the U.S. Congress legislated to eliminate compliance fines for the Corporate Average Fuel Economy (CAFE) standards. Previously, car companies increasing the sales of pure electric models can improve the overall average fuel economy of the company and reduce the pressure of fines caused by the sales of fuel-consuming pickup trucks and large SUVs. Two months later, federal tax and spending legislation was adjusted to completely terminate the federal tax credit of up to $7,500 for vehicles purchased after September 30.
The rush to buy before the expiration of tax credits pushed the penetration rate of new pure electric vehicles in the United States to a high of 10.6% in the third quarter of 2025, and then the market cooled rapidly. According to data from Cox Automotive, from the fourth quarter of 2025 to the second quarter of 2026, the penetration rate of new pure electric vehicles in the United States has hovered between 5.7% and 5.8%, with sales in each quarter falling by 36%, 27% and 20.5% year-on-year respectively.
In 2026, the United States will further relax regulations on fuel vehicles. In February, the Environmental Protection Agency revoked the identification of greenhouse gas hazards from motor vehicles and related emission standards; in September, the federal government lowered fuel economy requirements and made it clear that CAFE points transactions between car companies will be canceled starting in 2028. These adjustments have reduced the compliance pressure on auto companies selling fuel vehicles and also weakened their motivation to meet regulatory requirements by increasing the production and sales of pure electric models.
On the other hand, the advanced manufacturing tax credit policy, which is the mainstay of battery factory profits, has strengthened penetrating scrutiny of foreign investors and supply chains. In February 2026, the U.S. Internal Revenue Service issued guidelines to extend the relevant review of “foreign entities of concern” (FEOC) to foreign shareholders, debts, supply chains and technologies of battery companies. To apply for tax credits, companies need to verify the qualifications of investors and suppliers, trace material costs, and prove that production operations and technical cooperation arrangements meet the requirements for “actual control,” which increases the compliance costs of financing, procurement, and technology introduction.
As demand cools, car companies and battery companies have changed their original production expansion plans.
Large-scale bases that have been completed or are close to completion are mainly adjusted and operated by splitting joint venture assets, transferring equity, reducing production loads and switching to energy storage. The most typical one is the BlueOval SK project jointly owned by Ford and SK On. Ford took over the Kentucky campus, converted the first-phase power battery plant to energy storage, halved the production capacity, and found another use for the second-phase factory. The Tennessee plant was independently owned and operated by SK On, and the start of production was delayed.
For projects that have started civil construction or completed factory construction, they are more likely to choose to reduce investment, production capacity and job size, and postpone equipment installation and production to reduce subsequent capital expenditures. For example, the BlueOval lithium iron phosphate battery plant wholly owned by Ford in Michigan has reduced its investment commitment from US$3.5 billion to US$2.5 billion, its planned production capacity has been reduced from 35GWh to 20GWh, and its committed jobs have been reduced from 2,500 to 1,700.
Projects that are in the early stages of planning or expansion are exiting primarily by canceling construction, terminating leases, or selling sites. Norwegian battery company FREYR and American battery company KORE Power canceled their originally planned 34GWh and 12GWh battery cell projects respectively; silicon anode battery company Amprius terminated the expansion of new bases and retained existing R&D and small-scale manufacturing facilities; American battery company iM3NY sold assets after declaring bankruptcy; Natron Energy, which focuses on sodium-ion batteries, closed existing facilities and terminated new plant plans due to a break in the capital chain.
Most of the hundreds of gigawatt-hours of new production capacity planned in the last round of boom were not supported by real vehicle orders. Canceling the production expansion commitment that is still on paper is a way to correct and stop the irrational bubble.
From the perspective of production capacity supply and demand standards, according to the statistics of the International Energy Agency (IEA) “Global Electric Vehicle Outlook 2026”, as of the end of 2025, the nominal manufacturing capacity of lithium-ion batteries in the United States has reached approximately 330GWh (including power and energy storage). If we estimate that there are about 1 million pure electric vehicles sold annually in the United States and the electric charge of each vehicle is about 70 kWh, the annual demand for power cells on the local vehicle end is less than 80 GWh, accounting for only about a quarter of the nominal production capacity.
Car companies re-evaluate electric vehicles
Ford officially announced a major adjustment to its electrification strategy in December 2025, citing “lower than expected demand, high structural costs and changes in the regulatory environment” as the three main reasons. It will comprehensively reduce electrification capital expenditures and shift resources to fuel vehicles, hybrid models and more price-competitive next-generation pure electric platforms.
Since the second quarter of 2025, General Motors has accrued approximately US$10.9 billion in asset impairment and restructuring expenses related to electric vehicles; when Ford announced the contraction of its electrification strategy in December 2025, it accrued more than US$19 billion in one-time related expenses.
In the third quarter of 2026, GM sold approximately 25,000 electric vehicles in the United States, a year-on-year decrease of 62%. Ford sold approximately 6,000 units, a year-on-year decrease of 80%; the F-150 Lightning pure electric pickup truck, which had high hopes, only sold 289 units in a single quarter and has been discontinued.
However, amid the ebbing trend, the heads of the two major U.S. car companies insist that they “will not give up on electric vehicles.”
GM CEO Mary Barra admitted in public in 2026 that without federal subsidies, the popularization of electrification will take longer, but GM will still get there, and internal data shows that consumers who have purchased electric vehicles are 80% more likely to purchase them again. She said that GM still believes that electric vehicles are the endgame and its transformation mission has not changed.
Ford CEO Jim Farley placed the conditions for continuing investment in electric vehicles on specific costs and competitiveness. He recently stated in public that Ford’s internal disassembly calculations found that the battery procurement cost of BYD’s same-class vehicle is about 20% lower than Ford’s next-generation medium-sized electric pickup truck Fathom. In order to narrow the cost gap of the entire vehicle, Ford’s strategy is to redesign the motor, reducer and inverter, improve the efficiency of electric drive, and achieve the same range with a smaller battery pack. Farley also admitted that it is not easy to produce this car according to the established scale, cost and time, and the large-scale mass production engineering plan has not yet been finalized.
Car companies first need to adapt to the sales scale after the subsidy is withdrawn. According to Cox Automotive quarterly data, in the first three quarters of 2026, the sales volume of pure electric vehicles in the United States will remain at more than 200,000 units per quarter, with a market penetration rate of about 6%, roughly returning to the level from 2022 to 2023.
Car companies are also adjusting the proportion of investment in battery cell manufacturing assets. General sold its joint venture equity in the Lansing, Michigan, battery cell plant to LG New Energy in 2025, and transferred its equity in the battery plant under construction in New Carlisle, Indiana, to Samsung SDI in August 2026. After Ford took over the Kentucky joint venture park, it turned it to the energy storage market.
Through equity transfers and business divestitures, OEMs have transferred the depreciation pressure and capacity utilization risk of asset-heavy battery cell manufacturing to professional battery manufacturers and the energy storage market, and have retreated to vehicle platforms and system integration.
Explore the path to transition
Although new investment commitments have shrunk, many existing projects that have been intensively started in the past few years will still cross the acceptance node between 2025 and 2026 and enter the production or commissioning period. IEA data shows that the nominal manufacturing capacity of lithium batteries in the United States will increase by about 50% year-on-year in 2025, and the nominal production capacity at the end of the year will be about 330GWh. This includes approximately 60GWh of battery cell production capacity built in the United States by multinational car companies and Asian battery giants before this boom.
The supply chain tracking of the US Solar Energy Industries Association (SEIA) in September 2026 shows that the operating energy storage and dual-purpose battery cell manufacturing capacity in the United States is 62.3GWh/year, while the downstream energy storage module and battery pack assembly capacity reaches 107.6GWh/year. A large number of factories are located in the module and system integration links where capital expenditures are lower and construction cycles are shorter. Core batteries are still highly dependent on outsourcing or importing.
A comprehensive shift to the battery energy storage market is the most mainstream “self-rescue” channel for battery production lines originally planned to support electric vehicles. At a time when power batteries are in the cold, the transformation of the U.S. power grid and the expansion of artificial intelligence data centers are driving a surge in local energy storage installations. SEIA and Benchmark data show that new battery energy storage installed capacity in the United States will reach 57.6GWh in 2025, and 30.8GWh will be added in the first half of 2026. Among them, installed capacity in a single quarter in the second quarter will reach a record 20.2GWh. Institutions generally predict that new installed capacity in 2026 will be close to 70GWh.
The huge demand for energy storage has become the “takeover” for idle power production lines. In addition to the GM Ultium Tennessee plant mentioned at the beginning that will switch to producing soft-packed LFP energy storage cells in June 2026, the Ohio L-H joint venture between Honda and LG New Energy The Battery factory (originally planned to produce 40GWh automotive power cells) has taken the lead in mass-producing LFP energy storage cells in July 2026; the Lansing, Michigan, factory wholly owned by LG New Energy will be put into operation in August 2026, and will also prioritize the production of soft-core batteries. Including LFP energy storage cells, and has scheduled the mass production of square case LFP energy storage cells on the 2027 schedule; together with the Holland factory in Michigan that has started LFP energy storage production in May 2025, LG New Energy has intensively rolled out an energy storage manufacturing network in North America.
Other camps are also accelerating their entry. The first phase of the 33GWh factory in Kokomo, Indiana, a joint venture between Samsung SDI and Stellantis, is producing automotive batteries and is promoting production line conversion to supply the U.S. energy storage market; Envision AESC will sell a majority stake in the old Tennessee factory to FIXX, a U.S. company, in May 2026. Energy, the factory has completed the transformation of LFP energy storage cells and has produced a total of more than 4 million cells; Panasonic’s Kansas factory also disclosed in June 2026 that it plans to allocate part of its production lines to produce battery products for AI data centers from 2028 to 2029.
While switching to energy storage production, American battery companies are also exploring more technical routes. General Motors is laying out lithium-rich manganese-based batteries and is cooperating with Peak Energy to develop sodium-ion batteries for vehicles; iron-air, aqueous zinc and lithium-sulfur battery projects are advancing manufacturing and production ramp-up. Some companies have also shifted their business focus from passenger cars to defense, railways and industrial energy storage.
The focus of solid-state batteries is still pilot verification and engineering scale-up. QuantumScape will launch the Eagle pilot line in San Jose, California in February 2026 for trial production of solid-state batteries and customer delivery of samples for verification; Solid Power is promoting the installation of a pilot line for continuous manufacturing of sulfide solid electrolytes in Colorado and plans to launch it in the fourth quarter of 2026; Factorial will retain its US R&D and small-scale production facilities and shift large-scale battery manufacturing to South Korea.
These new technology routes provide differentiated breakthrough directions for existing assets. However, due to the megawatt-level pilot scale or long research and development cycle, they are far from being able to hedge against the gigawatt-level overcapacity in the United States in the short term. The development of some new technologies will even further exacerbate the risk of obsolescence of current production capacity.
Engineering capability bottleneck
Converting battery factories to energy storage production requires additional investment in equipment modification, product certification, and engineering personnel. From transformation to stable production, the engineering and compliance obstacles facing U.S. battery factories remain severe.
The first challenge is the high cost of modification and the strict certification cycle. Among the aforementioned production conversion plans, GM’s Ultium Tennessee plant and LG’s Lansing plant initially used the soft-pack LFP form. Ford Kentucky and LG chose square-shell LFP for subsequent planning, and some of Samsung SDI’s production lines first transitioned to the ternary material system.
Once changes are involved in the cathode material system (switching from ternary to LFP), cell physical size or packaging form (switching from soft package to square case), core processes such as coating, rolling, winding/lamination, liquid injection and even chemical packaging will need to be rebuilt on a large scale.
Changing car-standard power batteries to energy storage batteries also needs to meet the access requirements of electric utilities. To enter the U.S. power grid and industrial and commercial energy storage market, battery products must re-pass the energy storage battery safety standard (UL 1973), energy storage system safety standard (UL 9540), and stringent thermal runaway spread destructive testing (UL 9540A) and other standards.
In addition, large utility and grid customers often require cycle capacity retention commitments and long-term bankability guarantees of 10 to more than 15 years. Although converting energy storage to production can revitalize idle factories, it needs to deal with transformation costs, long certification cycles, and the cost gap with China’s mature LFP energy storage supply chain.
The second challenge is the engineering capabilities for high-yield mass production and the resulting cross-border manpower friction. Battery core manufacturing is a set of continuous physical and chemical processes that are extremely sensitive to environmental temperature and humidity, cleanliness and process windows, covering equipment installation, single machine debugging, entire line linkage, slurry and material parameter matching, engineering trial production, and ramping up to large-scale mass production.
Battery production is a typical system process amplification project. Small defects in the previous process will be accumulated and magnified layer by layer in the subsequent process. Troubleshooting and improving overall yield highly rely on front-line engineers’ experience in the relationship between front- and back-end processes.
Due to the long-term shortage of lithium battery manufacturing process engineers and skilled technicians in the United States, newly built factories need to dispatch overseas engineering and technical teams from South Korea, Japan and China to support them during the ramp-up period of equipment installation and commissioning. However, tight construction deadlines and the tightening immigration enforcement environment in the United States are causing severe friction.
In September 2025, a federal immigration enforcement incident broke out at the joint venture battery factory between Hyundai Motor and LG New Energy in Georgia. About 475 people were detained at the site, including more than 300 Korean technicians responsible for core equipment installation, production line commissioning and local employee training. This incident caused a complete interruption of the equipment installation in the factory, which was barely restored until some technical staff returned to work in November of the same year; in September 2026, more than 300 South Korean personnel involved formally submitted administrative claims to U.S. federal agencies and initiated federal infringement proceedings.
From a regulatory perspective, the U.S. Foreign Affairs Manual clearly allows equipment installation and debugging personnel who meet specific procurement contracts, have professional technical qualifications, and whose salary comes from abroad to apply for a B-1 business visa to work in the United States. In December 2025, a provision for professional training personnel was added.
However, in actual operations, the approval cycle for special visas such as B-1 is long, and battery production line debugging and troubleshooting are often sudden and urgent; some equipment manufacturers and subcontractors take “shortcuts” to enter the country to engage in on-site operations under pressure of construction schedules and costs, which can easily trigger immigration law enforcement risks. How to find a balance between strict compliance, long schedules and emergency production lines is still a problem that plagues multinational battery factories in the United States.
Therefore, the continued operation of the U.S. “Battery Belt” needs to make up for the gaps in local manufacturing capabilities in four aspects: personnel, production, supply chain, and engineering technology. The factory must first recruit and train local employees who are familiar with equipment operation and daily maintenance. Through continuous debugging and production, it can stably produce qualified cells. The supply of positive and negative electrode materials, separators, electrolytes and core production line spare parts also requires the gradual establishment of a supporting network with reasonable prices and timely delivery in North America. What takes more time to accumulate is the experience of the local engineering team, including troubleshooting complex process failures and product line changes and modifications, to continuously maintain the overall yield rate of the production line above the break-even line, and gradually reduce reliance on on-site guidance from overseas experts.
Source of title picture|Visual China
Return to the homepage to see more car information
Related Reading
- Anthropic engineer’s warning about Claude Code explains why tech outages could get much worse2026-11-22
- Original Unexpectedly, just one day after the APEC summit, China became famous around the world because of its three “specialties”2026-11-21
- Original Anthropic goes public and creates wealth: 96% of employees became millionaires overnight2026-11-20
- The beauties and handsome guys from UB.com want to enter your home and wait until they arrive.2026-11-20
- Original: Tencent’s shareholders will suffer again2026-11-20