一場涉及The massive theft of $6.3 billion in crypto assets shocked global financial markets.
In the early morning of October 30, Binance, the world’s largest crypto-asset trading platform, suffered a cyber attack. The stolen assets were equivalent to more than 42 billion yuan.
Binance promises to cover the losses. In the first nine and a half hours after withdrawals were resumed, the platform disclosed a net outflow of funds.$3.64 billion. However, some institutional investors have reduced their assets stored on Binance, but have not stopped trading through Binance.
They hope to reduce the risk of centralized custody, but cannot easily give up the liquidity of the top exchanges.
Blockchain analysis agencyElliptic estimates that the theft involved 11 blockchains and assets worth approximately $6.43 billion. Binance said it had replenished approximately 95% of the affected assets, and Elliptic confirmed that approximately US$2.85 billion in assets involved had been frozen or seized. Replenishing customer assets, freezing the funds involved and recovering stolen assets are three different processes.
In 2008, the Bitcoin white paper proposed an electronic cash solution that did not rely on a trusted third party. Eighteen years later, the crypto-asset market has re-formed a centralized platform for managing huge amounts of wealth, while traditional banks and payment institutions have begun to actively absorb related digital technologies.
$6.3 billion stolen, is blockchain the problem?
The blockchain can verify whether a transaction complies with the protocol rules, but it cannot confirm whether the initiator has obtained the legal authorization of the asset owner based on the transaction record alone. The security of the underlying network and the operational security of the trading platform are two different things.
Binance initially investigated and believed that the attack may have involved the compromise of a development and operations staff’s computer, but other intrusion points were subsequently discovered. As ofOn October 30, it announced that it had not found any evidence that the wallet private key had been leaked. The complete attack path still needs to be confirmed, and the existing data cannot prove that the underlying cryptographic algorithm of the blockchain has been cracked.
Once an attacker has sufficient system authority to initiate fund transfers, he or she may use normal on-chain processes to steal assets. Traditional banks have long established hierarchical authorization, job separation, abnormal transaction monitoring and internal auditing to prevent the authority risks caused by the centralized custody of huge amounts of wealth.
The first thing exposed by the Binance incident was the governance problem in asset control and transaction authorization. Technology can improve the efficiency of capital flow, but it cannot replace the management of authority and risk by operating organizations.
Why did decentralization give rise to centralized giants?
Bitcoin allows users to hold their own private keys and initiate transfers directly. But for assets to form an active market, price discovery, trade matching, fiat currency exchange, liquidity and account services are also required. The exchange grew from there.
The more concentrated buyers and sellers are, the easier it is to form deep order books and lower trading spreads. Liquidity attracts users, and more users bring greater trading volume. Scale and network effects continue to strengthen, and leading platforms therefore have market advantages that are difficult for latecomers to copy.
Business convenience also changes the distribution of control. By keeping the private key by themselves, users must bear the risk of losing the key and operating errors; when handing over assets to an exchange, the platform usually centrally manages the wallet and records the user’s rights and interests in an internal account. The legal ownership, actual technical control and daily operation authority of assets may be in the hands of different entities.
When Binance suspended withdrawals, the relevant blockchain was still running, but some users were unable to bypass the platform and withdraw custody assets. A market that originally hoped to reduce reliance on intermediaries has regenerated intermediary power that cannot be ignored.
There are major differences between exchanges and commercial banks in terms of assets and liabilities, business licenses, and regulatory systems, but the operational responsibility for centralized custody of other people’s wealth will not disappear. Decentralization can change the underlying transaction methods, and the market’s demand for liquidity and convenience will still promote the concentration of professional services to advantageous institutions.
US$3 billion is frozen, who has control of digital assets?
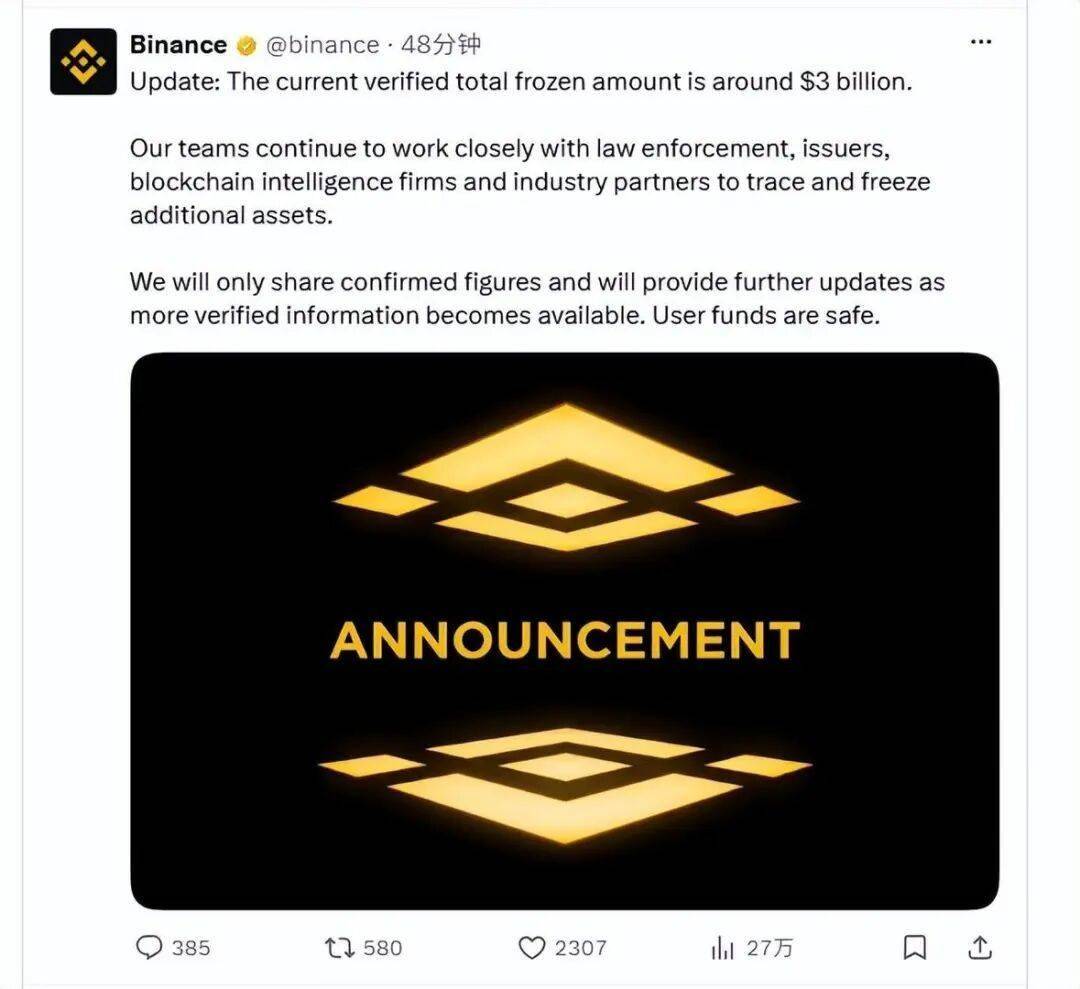
幣安稱約US$3 billion in assets involved have been frozen. Elliptic confirmed that approximately $2.85 billion had been frozen or seized as of November 1, of which approximately 94% belonged to stablecoins. Why do assets running on the same blockchain have different disposal results?
The native assets of Bitcoin and Ethereum do not have a central issuer that can uniformly freeze the balance of ordinary addresses.Stable coins such as USDT and USDC have clear issuing entities, and relevant contracts can restrict the flow of tokens from some addresses under specific conditions. The attacker therefore attempted to exchange some of the stablecoins for assets that did not have the same freezing mechanism before the freeze took effect.
Blockchain records can help track whereabouts, but they cannot directly complete asset recovery. Even if the assets involved in the case are frozen, the final return still requires ownership identification, legal procedures and cross-border cooperation.On October 31, the FBI attributed the attack to the North Korea-related Trader Traitor organization and called on relevant agencies to help block the flow of funds involved.
For holders, self-custody reduces the control of exchanges and may lack convenient error correction and relief channels; institutional custody provides transaction convenience, but introduces operational risks; stablecoin issuers have freezing authority and can assist in dealing with theft, and also form new management powers.
Who controls the assets, who can intervene after a dispute occurs, and who bears the final loss constitutes another set of competitive conditions for digital financial services. For businesses and ordinary users, the ability to recover after theft or erroneous transfers are as important as the transfer speed.
Binance promises to tell the truth, how much is platform credit worth?
Binance announces arrangements overUS$6.34 billion in resources were used to replenish the affected assets, and it was said on November 1 that approximately 95% of the assets had been completed. This is the backfill progress disclosed by the company. It does not mean that 95% of the stolen money has been recovered, nor can it replace the independent audit of all assets, liabilities and solvency.
After the platform announced that it would bear the losses, customers were still making new choices. Binance reveals net outflows in first nine and a half hours after withdrawals resume$3.64 billion. The company said withdrawal pressure has stabilized, but third-party statistics gave different estimates.
Other institutions have not stopped using Binance. According to Bloomberg,The chief investment officer of Kronos Research said he would not withdraw funds, citing that Binance still has significant trading liquidity. SQS Trading originally held about a quarter of its trading capital in Binance and plans to reduce this amount by about one-third, but it will still conduct hedging transactions through Binance.
Institutions not only want to reduce the risk of centralized custody, but also do not want to lose the trading depth of the top market. Leaving the platform may reduce one type of risk, but may also result in wider transaction spreads, higher execution costs, and more difficult risk hedging.
In 2025, Binance and institutional custody partner Ceffu launched MirrorRSV, allowing qualified institutions to leave assets in an over-the-counter custody structure while using Binance’s trading services. In February 2026, Binance cooperated with Franklin Templeton to use third-party managed tokenized money market fund shares as collateral for institutional transactions.
These arrangements attempt to preserve the liquidity value of the trading network while reducing the size of assets that customers must deposit directly with the exchange. However, third-party custody, collateral valuation, transaction settlement and counterparty performance still generate new risks and costs. Risks can be reallocated but will not disappear due to changes in organizational form.
How much wealth a platform can gather and how much wealth it can safely manage are two different business capabilities. The number of transactions a customer completes on the platform does not always increase in tandem with the amount of assets deposited. The future competition of exchanges will not only compete for liquidity, but also need to win customers’ trust in asset control arrangements.
System security and compliance are ongoing expenditures, and capital and liquidity guarantees occupy resources. Once an extreme accident occurs, it may cause huge one-time losses. Only calculating transaction fees and matching efficiency cannot reflect the complete cost of financial services.
A one-time bailout can alleviate the crisis of trust, but cannot prove that all extreme losses can be tolerated. Certificates of reserves provide partial transparency and are not a substitute for a full financial audit.
Risk-taking ability itself is a kind of operating ability.
Why does traditional finance actively embrace blockchain?
Unlike crypto-asset platforms exploring the separation of transaction services and asset custody, traditional financial institutions are transforming payment, settlement and fund dispatch within the existing credit system to shorten the time of funds in transit and reduce cross-institution coordination costs.
Visa disclosed at its earnings conference call on October 27 that the annualized scale of its stablecoin settlement business has exceeded US$25 billion, a year-on-year increase of approximately 10 times; the Visa Direct stablecoin prepaid fund service has also entered some commercial applications from pilot projects. The annualized scale does not represent the annual transaction volume that has been completed, nor does it represent the same scale of terminal goods and service consumption, but the relevant technology has entered the actual business process of payment institutions.
If the new settlement method can break through the limitations of traditional bank business hours and shorten the time that funds are in transit, financial institutions may reduce the occupation of part of their working capital. However, compliance review, exchange, liquidity management and risk disposal costs still need to be included in complete calculations.
摩根大通On October 19, it was announced that JPM Coin would be extended to the Ethereum mainnet for qualified institutional customers to use USD deposit tokens. Swift announced in July that 17 banks were preparing to launch a cross-border payment pilot for tokenized deposits. In August, Standard Chartered Bank and HSBC completed the first cross-border tokenized deposit interoperability transaction on the Swift blockchain ledger. The relevant ledger is responsible for coordinating and matching the transaction obligations of the two banks, and the final settlement is still completed through the existing system.
The credit basis of JPM Coin is still commercial bank deposits and cannot be confused with Bitcoin or private stable coins. Banks are using new technologies to transform their original businesses without giving up deposit credit and corresponding institutional guarantees.
In March 2026, a study published in the IMF working paper series, combined with the stock price reaction before and after the key vote on the U.S. Stablecoin Act, and the market’s changes in the probability of passing the bill, estimated that the relevant legislation would have a negative market value impact of approximately 18% on traditional listed payment companies, totaling approximately US$300 billion. This is a model estimate made by the researcher based on market prices. It does not mean that the company has lost corresponding operating income.
The study found that companies with a higher proportion of cross-border payment business will be more affected, while companies with network effects or that have already developed encryption-related businesses will be less affected. New technologies may impact the original charging model, or they may be absorbed by companies with customer networks, capital strength and institutional credit.
Three thresholds that will determine the future of cryptocurrency
Financial innovation brought about by digital technology does not necessarily translate into the growth of private cryptocurrencies. Open encrypted assets such as Bitcoin rely on protocol rules and market supply and demand to find usage scenarios in investment and specific value transfers; legal currency-backed stablecoins rely on issuing institutions, reserves and redemption capabilities to explore applications in cross-border payments and on-chain settlements; central bank digital currencies and tokenized bank deposits improve payment and settlement efficiency within the existing currency credit system. The latter is not an extension of private cryptocurrencies and may also compete with them.
The institutional environment for different paths is also diverging. USAThe “GENIUS Act” will be signed in 2025 to establish a regulatory framework for stablecoin payments; the EU implements unified supervision through MiCA. In February 2026, Mainland China issued an eight-department notice to continue to strictly prohibit related domestic virtual currency trading businesses while promoting the development of digital renminbi.
In January 2026, digital RMB 2.0 will be launched, and eligible real-name wallet balances will begin to accrue interest; on October 21, the central bank’s digital RMB system and smart contract ecological service framework will be further upgraded. China’s promotion of the digitization of legal tender and the opening of private crypto-asset trading markets have different institutional goals.
Currency not only undertakes the payment function, but also involves pricing, credit, settlement and financial stability. Technology can change the way funds flow, but it cannot alone determine where money and credit come from and who bears the losses.
A huge theft is not enough to deny the future of the entire industry, nor does the continued expansion of the market scale prove that the business model has matured.
The cryptocurrency industry must first cross the threshold of real demand. Whether open encrypted assets can form sustainable usage scenarios, and whether stablecoins can prove their value in real payments and settlements, will determine how much market space technological innovation can be transformed into.
Second is credit and risk. Whether issuing institutions and trading platforms can establish asset protection, risk management and continuous performance capabilities that match the asset size determines how much wealth the market can carry.
The third threshold comes from competition. When traditional banks and payment institutions begin to absorb blockchain and tokenization technologies, some of the technologies and service models pioneered in the crypto-asset industry may not always be exclusive to existing platforms. Whether the first-mover advantage of technology can be transformed into a competitive advantage that is difficult to replace will determine the long-term status of existing platforms in the transformation of the financial system.
Related Reading
- Nvidia live updates: Jensen Huang ousted, CFO Colette Kress to serve as interim CEO2026-11-13
- Are mangoes not afraid of red fruits?2026-11-12
- Original: After Huang Renxun, who is most likely to take over Nvidia?2026-11-12
- Samsung’s roll-screen mobile phone is exposed, creating a new form ahead of Huawei and Apple, and folding screens are expected to be eliminated2026-11-12
- Musk’s favorite car is going to be discontinued.2026-11-12


