Bursting the new car order bubble
34萬
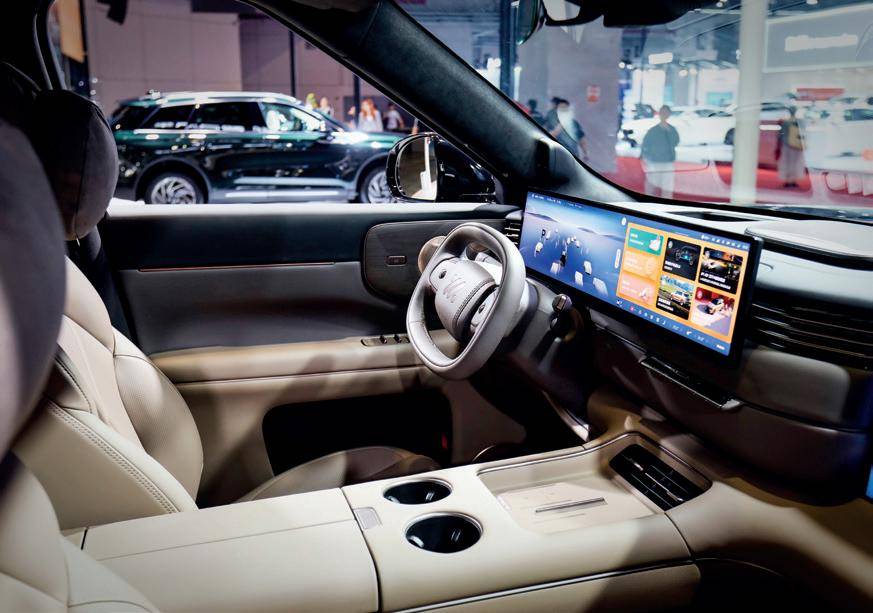
Order battle reports cannot support real demand. Pulse marketing collides with the stock game, the new car bubble recedes, and competition will eventually return to system capabilities
Text | “Finance” special writers Song Liwei and Yang Zheng
Editor|Zhao Cheng
In May 2026, after the Xiaomi YU7 standard version and GT version were released, Lei Jun, chairman and CEO of Xiaomi Group, stated that instant order data for subsequent new cars would no longer be announced to the public. Lei Jun said that the reason for this move was that when YU7 was first launched a year ago, the company announced that it would break 200,000 units in 3 minutes and 240,000 units in 18 hours, which attracted industry attention.
Looking back to 2025, announcements that new car orders exceeded 10,000 in 24 hours or even exceeded 10,000 in minutes once became a very common part of the new car launch process.
However, when new cars actually start being delivered, and when market observers start to reconcile the actual sales data with the number of orders, they often find that there is a lot of water and bubbles in the initial beautiful orders. Order data that should be used as a reference for decision-making by consumers, car companies and investors has repeatedly turned into illusory marketing competitions.
In September 2025, NIO founder, chairman and CEO Li Bin publicly pointed out that if the order numbers announced by various brands are added up, the total will reach 100 million units. In fact, according to statistics from the China Association of Automobile Manufacturers (hereinafter referred to as the “China Association of Automobile Manufacturers”), the cumulative sales of passenger cars in China in 2025 will be 30.103 million units. Li Bin compared order marketing to the “inflation” of the industry, saying that this behavior can easily put the company itself into a dilemma of mismatch between expectations and delivery.
Due to the dual influence of public opinion constraints and the market environment, entering 2026, the popularity of “order marketing” in the automotive industry has subsided. In the first quarter, the industry even ushered in a “quiet period” for order disclosure. However, since April, some key models have restarted order reporting promotions and ushered in a small peak in May. Different from 2025, in order to avoid disputes caused by intended orders or small orders, since 2026, some car companies have also shifted to emphasizing relatively restrained “large-scale” quantities or locked-in orders.
But regardless of whether the order is large or small, the true supply and demand relationship will eventually be tested in the terminal delivery data. According to incomplete statistics, from January to July 2026, 23 key new cars have publicly disclosed order data of different statistical calibers, including Xiaomi YU7, Wenjie M6, the new generation Wenjie M9, Zhijie V9, Xpeng GX, Lantu Taishan 8X, etc.
Statistics show that these models are all new energy vehicles, covering pure electric, plug-in hybrid and extended-range power forms. By comparing order volume with actual sales as of September, Caijing found that only two models fulfilled initial orders within one month of launch, and only six models fulfilled initial orders within three months of launch. The conversion cycle for over 60% of the remaining models exceeds four months, and there is a huge gap in the conversion of large order orders for some models to actual terminal delivery.
In fact, after crossing the initial conversion threshold, most models reach peak sales in about three months after being launched, and then sales decline rapidly. At the 2026 Smart Electric Vehicle Development High-Level Forum, Li Bin called this phenomenon the “Valley of Death” for new cars.
Li Bin’s metaphor may be exaggerated, but the stagnation and sharp turn in the order conversion process essentially reflect the switching of the industry’s growth logic. McKinsey pointed out in “McKinsey China Automotive Consumer Insights 2026” that “price wars” are eroding consumer confidence. Simply cutting prices is not only unable to stably drive transactions, but also intensifies the wait-and-see mood.
When orders that are blindly driven up are deviated from the real endogenous consumer demand and delivery rhythm, car companies that are accustomed to relying on impulse marketing and production-based sales to drive scale need to be wary of the operating costs that may be brought about by order bubbles.
Unfulfilled orders
Do the new car order volumes announced by car companies represent the real feedback from the market? With this question in mind and considering the ramp-up cycle of new car production capacity, “Caijing” sorted out the key models that will be launched in the first seven months of 2026 and have announced order data.
However, third-party data shows that as of the end of September, the cumulative wholesale sales of MG07 were only 17,857 units. In the 41 days since its launch, its actual wholesale sales scale has only reached 57.6% of the large lock-in order of 31,000 units, and only 30.27% of the intended small order of 59,000 units. The wholesale conversion loss is obvious.
Two key models of Chery Fengyun series also encountered conversion obstruction. Chery Fengyun A9 started small pre-orders in April, pre-sales started on July 9, and was officially announced on July 25. According to the company’s official disclosure, 18,173 units of the car were pre-sold within 72 hours, and the cumulative number of pre-sales exceeded 31,729 units within 15 days. However, as of September, the cumulative sales of Fengyun A9 were only 8,691 units, which only reached 27.39% of the large orders in the pre-sale stage. There was a gap of more than 20,000 units between orders and actual sales.
Fengyun T9L, which is mainly a plug-in hybrid five-seater SUV, started pre-sale in March, and the cumulative pre-sale orders reached 21,248 units. In April, the car was officially launched and delivered. Although the entry-level replacement subsidy price of the car was reduced by 14,000 yuan from the pre-sale price, as of September, its cumulative sales had only completed 75.5% of the pre-sale order size, reaching 16,037 units.
Products targeting the higher-end market also face the problem of insufficient order fulfillment.
Even for high-end products that previously had strong brand appeal, long-term delays in the order conversion process have become the norm.
For example, JiKrypton 8X. The car started pre-sale in March and will be launched on April 17. The company stated that pre-sales of the car exceeded 30,000 units within 48 hours, and large orders exceeded 10,000 units within 29 minutes of its launch. Thanks to the price reduction of nearly 50,000 yuan, although the Jikrypton 8X won the sales championship of hybrid SUVs with a range of 300,000 to 500,000 yuan in the same period, the cumulative sales volume of the car was 22,000 units in 167 days, which was only 73.33% of the pre-sale intention of small orders of 30,000 units. The delivery conversion gap is clearly visible.
Zhiji LS8, which also started pre-sale at the end of March, achieved a record of over 10,000 small orders in 45 minutes. In April, the car was officially launched, and the company officially announced that the new car is expected to sell over 8,000 units in 60 minutes. By the end of September, after 168 days, the cumulative sales of this car were less than 10,000 units. Although it crossed the large-scale line, it still failed to reach the small order scale during the pre-sale period.
Huawei’s deeply empowered Hongmeng Zhixing series is also under pressure from a prolonged cycle. The new generation of Wenjie M9 started pre-sales on April 22, and pre-sale orders exceeded 70,000 units within 72 hours; pre-orders exceeded 11,000 units within one hour of launch on May 27. On June 27, Yu Chengdong, Huawei’s Managing Director, Director of the Product Investment Review Committee, and Chairman of Terminal BG, posted on his personal Weibo that the new generation of the M9 series was expected to exceed 42,000 units within one month of its launch. However, third-party statistics show that in the four months from June to September 2026, the cumulative sales of Wenjie M9 were 39,856 units, and the terminal delivery volume has not yet fully covered the large scale announced in the first month of launch. Not only that, due to the impact of product generation switching and intensified market competition, as of September, the cumulative sales of Wenjie M9 in 2026 were approximately 57,000 units, a year-on-year decrease of nearly 40%.
For the first-generation hot model Xiaomi YU7, the order intake spanned a whole year. In June 2025, when Xiaomi YU7 was launched, officials revealed that more than 240,000 units were locked in orders within 18 hours. However, public data shows that from June 2025 to May 2026, it took a year for the cumulative sales of YU7 to reach 243,908 units.
Among the statistical models, as of the third quarter, only a few models have outperformed initial orders. Among them, Jihu Beta S3 has sold a total of 32,339 units from its launch on May 22 to September 30, and its wholesale sales exceeded the 30,000-unit order volume during the pre-sale period. Xpeng GX, which also adopted a strategy of significantly lowering its price, ordered 24,863 units within 12 hours of its launch. As of September, the cumulative sales volume was 27,805 units, and it took more than four months to exceed the initial order list.
New car “Death Valley”
If the order conversion rate tests the true customer locking ability of a new car, then the sales life cycle curve after the launch exposes the deep shortcomings of car companies in product definition and continuous operations. Among the key models sorted out by Caijing, most of them fell into what the industry calls the “Valley of Death for New Cars” three to four months after they were launched. This concept was proposed by Li Bin at the 2026 Intelligent Electric Vehicle Development High-Level Forum to describe the industry phenomenon in which new cars surge in popularity in the short term based on the pulse of launch. After the popularity subsides, sales plummet and the hot-selling window narrows significantly.
The two new mass-market products of Huawei Hongmeng Smart have a consistent parabolic trajectory. Among them, Zhijie V9’s one-hour pre-sale orders exceeded 12,500 units in April, which lasted nearly four months. It was only in July that the cumulative sales exceeded the pre-sale orders with 16,954 units. It is worth noting that after the car exceeded the 10,000-unit mark with a multiple increase in July, it then turned downward at almost the same rate. By September, its monthly sales had quickly fallen to 3,542 units.
Other independent new energy brands are also facing declines after rapid rises.
The Qijing GT7, jointly built by GAC and Huawei Qiankun, started blind ordering in March and exceeded 20,000 orders in three days. It was officially launched on June 26 and officially disclosed that the order volume exceeded 5,200 units in 24 hours. As of August, its cumulative wholesale sales reached 5,369 units. After hitting a delivery peak of 2,998 units in July, wholesale sales halved to 1,330 units in August, and accelerated to 376 units in September.
Great Wall Weipai V9X was launched in May. The sales volume in the month of launch was 1,018 units. After a short period of time, it climbed to a peak of 1,855 units in July. It fell back to 1,035 units in August and further dropped to 681 units in September, which was about 61% smaller than the peak. The cumulative sales volume in the five months since its launch was only 6,094 units. It also peaked and fell in the third month of its launch.
The intelligent transformation projects of joint venture car companies have not been spared. NX8, the first all-new model of Dongfeng Nissan Tianyan Architecture 2.0, was launched on April 8 with a guide price starting from 159,900 yuan. The limited-time equity price was reduced to 149,900 yuan. Officially announced orders reached 8,423 units within one hour of launch. As of June, its cumulative sales were close to 12,000 units. However, after hitting a monthly peak of 5,398 units in May, sales in September have dropped sharply to 2,695 units, a cut of more than 50% from the peak.
廣汽豐田The first pure electric car equipped with Hongmeng cockpit and lidar smart driving鉑智7, pre-sales started in March, and orders exceeded 10,000 units in 24 days. It took four months to build the car, and as of the end of June, a total of 10,351 units had been delivered, and the pre-sale order had just been completed. Monthly sales fell rapidly after reaching a peak of 4,637 units in April, falling to 1,757 units in June, a trough drop of 62.1%. In the following months, the sales stabilized at around 2,000 units, never regaining the momentum of the initial launch.
Even Xiaomi Motors, which made waves last year, is facing a test of its vitality after product iterations. On May 21, 2026, Xiaomi YU7 family added two new models, standard version and GT. Third-party data shows that with the support of the two new versions, the cumulative sales of the Xiaomi YU7 family in the four months from June to September were only 50,000 units, with a monthly average of 12,500 units. In December 2025, the peak monthly sales of YU7 reached 39,089 units. Now, the average monthly delivery volume in the past four months has dropped by nearly 70% from the peak.
This widespread phenomenon of “the peak is when it is launched and will be cut in half in March” is a concrete manifestation of the deep-seated contradictions in the current Chinese automobile industry.
Zhang Yongwei, chairman of the Auto Baihui Research Institute, pointed out that there are currently too many models on the market, and most of them are just fine-tuned facelifts. Products that truly have underlying platform innovation are rare. “The contradiction between multiple models and bicycle sales scale is the main contradiction at present. There are many varieties and styles, but the scale of bicycles cannot increase. Such a development model is unsustainable.” Zhang Yongwei said.
Zhang Yongwei further analyzed and pointed out that the cumulative sales of some new cars in a year are only a few thousand or 10,000 units, which cannot form economies of scale and cannot support the sustainable development of the company. Enterprises are accustomed to relying on a single hot product to drive them. However, once the life cycle of these two products is cut in half after a few months on the market, the enterprise’s own ability to resist risks will be completely out of balance.
The strategy of promoting new cars at low prices and facelifts not only makes it difficult to maintain the long-term vitality of the models, but also drags the entire industry into an extremely fragile financial quagmire.
When profit margins are low and it is difficult for bicycles to achieve economies of scale, the traditional path of relying on press conferences to rush illusory orders and relying on price cuts to stimulate instant demand has completely failed. Zhang Yongwei emphasized that the stage of driving the development of the industry with high growth has passed. Auto companies must shift from single-point competition that relied solely on a certain popular product in the past to a comprehensive competition that competes on organizational efficiency, operational quality, and global structure.
Dismantling the stock game
The cliff-like decline in new car conversions and the bottoming out of corporate profitability are only a microscopic aspect of the fluctuations in China’s auto market in 2026. Looking to the first three quarters, the entire domestic automobile consumer market is undergoing an unprecedented and drastic structural reshaping. In the existing market, the game between car companies and new cars is the root cause of frequent order bubbles.
The China Automobile Association pointed out that due to multiple factors, the domestic automobile market continued to be under pressure in the first three quarters and has not yet been effectively improved. Macroscopic statistics confirm this trend. In the first three quarters, China’s automobile production and sales completed 23.246 million units and 23.271 million units respectively, both down 4.5% year-on-year. Among them, domestic sales were 15.066 million units, a year-on-year decrease of 22.4%. In the passenger car sector, production and sales were 19.966 million units and 19.96 million units respectively, down 6% and 6.1% year-on-year. Among them, total domestic sales fell to 12.794 million units, down 24.9% year-on-year.
Cui Dongshu, secretary-general of the Passenger Car Market Information Joint Branch of the China Automobile Dealers Association, believes that the passenger car market in the first three quarters has been characterized by deep year-on-year pressure on the total volume and extremely amplified structural differentiation. In September, the decline of fuel vehicles accelerated, and the resilience of new energy vehicles became the main line of the market. Behind this, high oil prices are continuing to have a severe impact on the consumption of traditional fuel vehicles, accelerating the pace of “oil and electricity substitution”.
Statistics from the China Automobile Association show that in the first three quarters, sales of traditional fuel vehicles in the domestic market were 6.599 million units, a significant year-on-year decrease of 33.6%. Specific to the field of passenger cars, sales of traditional fuel passenger cars dropped to 5.127 million units, a decrease of 3.014 million units from the same period last year, a year-on-year decrease of 37%.
Cui Dongshu further pointed out that independent, mainstream joint ventures and luxury brand fuel vehicles have all been hit by high oil prices indiscriminately. Domestic retail sales of pure fuel passenger vehicles have almost halved, and only general-hybrid models are relatively strong.
While fuel vehicles are retreating across the board, new energy vehicles have played a ballast role in the domestic market. According to statistics from the China Association of Automobile Manufacturers, in the first three quarters, the production and sales of new energy vehicles in China were 12.483 million and 12.472 million respectively, a year-on-year increase of 11% and 11.1% respectively. The sales of new energy vehicles have accounted for 53.6% of the total sales of new automobiles. Among them, the proportion of domestic sales of new energy passenger vehicles has climbed to 59.9%.
In addition to passenger cars, the commercial vehicle market is showing an inverted phenomenon of “heating outside and cooling inside”. Data show that in the first three quarters, China’s commercial vehicle production and sales completed 3.279 million units and 3.311 million units respectively, a year-on-year increase of 6.1% and 6.2% respectively. However, its domestic sales were only 2.272 million units, a year-on-year decrease of 4.1%. Among them, the domestic sales of trucks, which are a barometer of the national economy, were 1.968 million units, a year-on-year decrease of 5%.
However, the historic breakthrough in the penetration rate of new energy vehicles and the rising share of independent brands have not been able to fully offset the overall operating pressure of the industry. In the deep game of the existing market, the “price war” has caused car companies to be attacked from all sides. Cui Dongshu said that from January to August 2026, the operating income profit margin of the automobile industry further bottomed out to 3.6%.
Cui Dongshu pointed out that the demand for AI (artificial intelligence) has driven the rise in chip prices, and the prices of upstream non-ferrous metals and other raw materials are also rising. Combined with the serious wait-and-see mentality of end-users when purchasing cars, the profitability of the automotive industry is poor, and development is being greatly impacted by both the upstream and downstream ends.
Corporate financial reports also confirm the industry’s dilemma of increasing revenue without increasing profits. Statistics from Caijing show that in the first half of 2026, the 15 major listed vehicle companies in the domestic passenger car field had a total revenue of 1.43866 billion yuan, but the total net profit attributable to the parent company was only 21.8 billion yuan, and the overall net profit rate was as low as 1.52%. Chen Shihua, deputy secretary-general of the China Automobile Association, said that in the first half of 2026, the average profit margin of the entire vehicle manufacturing process will drop to 1.5%, a sharp decrease of 43% year-on-year, the lowest in the past decade.
Faced with the short-term downward pressure on the domestic market, the China Automobile Association looks forward to the fourth quarter and believes that with the release of all 250 billion yuan of trade-in funds for consumer goods, the effectiveness of the implementation of stock policies will be further enhanced, coupled with local and corporate consumption promotion activities, the decline in sales in the domestic market is expected to narrow.
The contraction of domestic demand and the bottoming out of profits have pushed the same problem to the front of car companies. When the domestic mass market can no longer rely on pulse order marketing and production-based sales to digest the established production capacity and product rhythm, growth can only be found elsewhere. The order bubble and the surge in overseas exports are not two isolated stories. The former is a marketing substitute after the domestic market growth logic fails, and the latter is a survival path forced to speed up after the same logic fails. Domestically, it relies on press conferences to support its reputation and channel confidence, while overseas relies on asset-heavy layout and system capabilities in exchange for profits and scale. The two are two sides of the same coin. In this sense, to understand the outcome of the order bubble, we must not only look at domestic delivery data, but also look at the methods and costs in which Chinese car companies are reorganizing a sustainable growth structure in overseas markets.
Anchoring and breaking out at sea
When domestic demand enters a deep adjustment cycle, overseas markets are not only a floodgate for Chinese car companies to digest production capacity, but also a strategic lifeline to support the industry and maintain corporate profits. Guosheng Securities pointed out in a research report that in the first eight months, there was a sharp differentiation between the slowdown in domestic demand and the high growth in overseas markets. The overseas layout capabilities of automobile companies have become the core variable that determines the direction of performance and valuation.
Statistics from the China Association of Automobile Manufacturers show that China’s automobile exports showed strong growth resilience in the first three quarters, with national automobile exports totaling 8.205 million units, a year-on-year increase of 65.8%. Among them, passenger cars are the main force driving the surge in exports.
Specifically, in the first three quarters, China’s passenger vehicle exports reached 7.167 million units, a year-on-year increase of 70.6%; the commercial vehicle sector also accelerated its spillover, with a total export of 1.039 million units, a year-on-year increase of 38.8%. Southwest Securities research report analysis shows that the basic market of Southeast Asia and Africa combined with incremental markets such as Latin America and Central Asia has made commercial vehicle exports a key support to resist the weakening domestic demand for commercial vehicles.
The explosive spillover of new energy vehicles is comprehensively restructuring the power structure of China’s automobile exports. Data show that in the first three quarters, China exported a total of 4.006 million new energy vehicles, a year-on-year increase of 1.3 times. The proportion of new energy vehicles in exports has exceeded 50% for four consecutive months, completely changing the previous export pattern dominated by fuel vehicles.
Broken down, the technical roadmap shows many developments. In the first three quarters, 2.449 million pure electric vehicles were exported, a year-on-year increase of 1.2 times; plug-in hybrid electric vehicles were exported 1.557 million units, a year-on-year increase of 1.5 times, and the growth rate significantly outperformed pure electric models.
Cui Dongshu said that despite some external interference recently, China-made narrow plug-in hybrid models have continued to gain market acceptance in developing countries, with demand growing rapidly.
At a micro level, going overseas is profoundly reshaping the sales and profitability patterns of auto companies. According to statistics from Guosheng Securities, in the first half of 2026, Chery exported 940,000 vehicles, a year-on-year increase of 71.5%; BYD exported 790,000 vehicles, a year-on-year increase of 70.6%; Geely exported 470,000 vehicles, a year-on-year increase of 157.6%; Leap Motors exported 100,000 vehicles, a year-on-year increase of more than 3.7 times. Exports have surpassed domestic demand and become the core focus of some car companies, and the export proportion of some car companies has exceeded 50%.
From a global perspective, in the first eight months, China’s share of world automobile sales reached 32.0%. In the field of new energy, China’s share of new energy passenger vehicles in the world is as high as 62%, of which plug-in hybrid models account for 71% of the world market, forming a supply-leading position in the global electrification transformation.
However, behind the prosperous export curve, the globalization breakthrough of Chinese car companies is entering a deep water zone, with hidden worries and challenges coexisting. The first thing to bear the brunt is the exchange and compliance costs on the financial side.
Affected by the fluctuations in the international financial environment, the increase in overseas expansion is not without cost. The financial report shows that in the first half of the year, Chery Automobile’s net exchange loss reached 2.092 billion yuan, Geely recorded a net exchange loss of 550 million yuan, Great Wall lost about 266 million yuan after excluding exchange lock hedging, and Changan Automobile also incurred a net exchange loss of 230 million yuan.
The deeper resistance comes from the increasingly stringent external trade environment and geopolitical barriers. Zhang Yongwei pointed out that China’s automobile industry is currently facing strong constraints in four major dimensions when going global: First, the risk of choosing sides caused by geopolitics; second, there is no possibility of lowering tariff barriers; third, non-tariff barriers and forced technology transfer requirements are increasing; fourth, localization protection is tightening globally. Not only has the European Union introduced the Industrial Accelerator Act to increase procurement restrictions, but emerging markets in Southeast Asia have also put forward rigid demands for local employment, taxation and parts procurement.
The “goods going overseas” model that relies solely on the trade of finished vehicles is hitting the ceiling, and in-depth evolution of the industrial model is imperative.
Zhang Yongwei believes that Chinese automobiles must accelerate the transition from trade exports to all-round “system overseas”. On the one hand, car companies need to adopt diversified strategies such as new construction, acquisitions, leasing and even overseas OEMs to solidly promote the localization of overseas heavy assets; on the other hand, they should integrate into the local industrial ecology through competition and cooperation models such as technology licensing and joint venture empowerment to resolve trade barriers. At the same time, it is promoting the transformation of multinational enterprises in China from “in China, for China” to “in China, for the world”, and relying on their mature overseas channels and compliance networks to break through collaboratively.
McKinsey also emphasized in its “2026 China Automobile Consumer Insights” that the competitive unit of China’s auto industry is expanding from a single enterprise to a collaborative system of “OEM + supply chain”. Facing the long-term uncertainty in the global market, the future winners will be those auto companies that can consolidate the technological innovation, intelligence and energy-replenishing experience forged in China into a stable system and promote it to the world in a customized way.
In the first year of the “15th Five-Year Plan”, the China Association of Automobile Manufacturers predicts that automobile exports will maintain a steady growth trend in the fourth quarter, and the total export volume in 2026 is expected to exceed 10 million vehicles. While crossing the historical threshold of tens of millions of vehicles, bidding farewell to barbaric growth, deeply cultivating the local ecology and building a global system will be the footnote of the era for China to move from a major automobile country to a powerful automobile country.
Return to the homepage to see more car information
Related Reading
- Nvidia live updates: Jensen Huang ousted, CFO Colette Kress to serve as interim CEO2026-11-13
- Are mangoes not afraid of red fruits?2026-11-12
- Original: After Huang Renxun, who is most likely to take over Nvidia?2026-11-12
- Samsung’s roll-screen mobile phone is exposed, creating a new form ahead of Huawei and Apple, and folding screens are expected to be eliminated2026-11-12
- Musk’s favorite car is going to be discontinued.2026-11-12


