In June 2026, a cross-border remittance was sent from the Bank of China, crossing the 12-hour time difference across the Pacific Ocean, and was credited to JPMorgan Chase in quasi-real-time, with the whole process taking less than 60 seconds.
Bank of China and JP Morgan Chase jointly announced that the two parties have cooperated to complete the first real-time personal cross-border remittance transaction between China and the United States. In addition to the U.S. market, Bank of China has also established “BOC Instant Remittance” business connectivity with major partner banks in the United Kingdom, Australia, and Spain.
After trials in key cities, during this year’s Service Trade Fair, Bank of China stated that it will launch “BOC Instant Remittance” nationwide on September 13 to provide individual customers with faster and more transparent cross-border remittance services.
Behind a remittance is the intersection of a century of cross-border financial accumulation and a new generation of payment technology.
From overseas Chinese batches to instant remittances, Bank of China’s century-old heritage of cross-border services
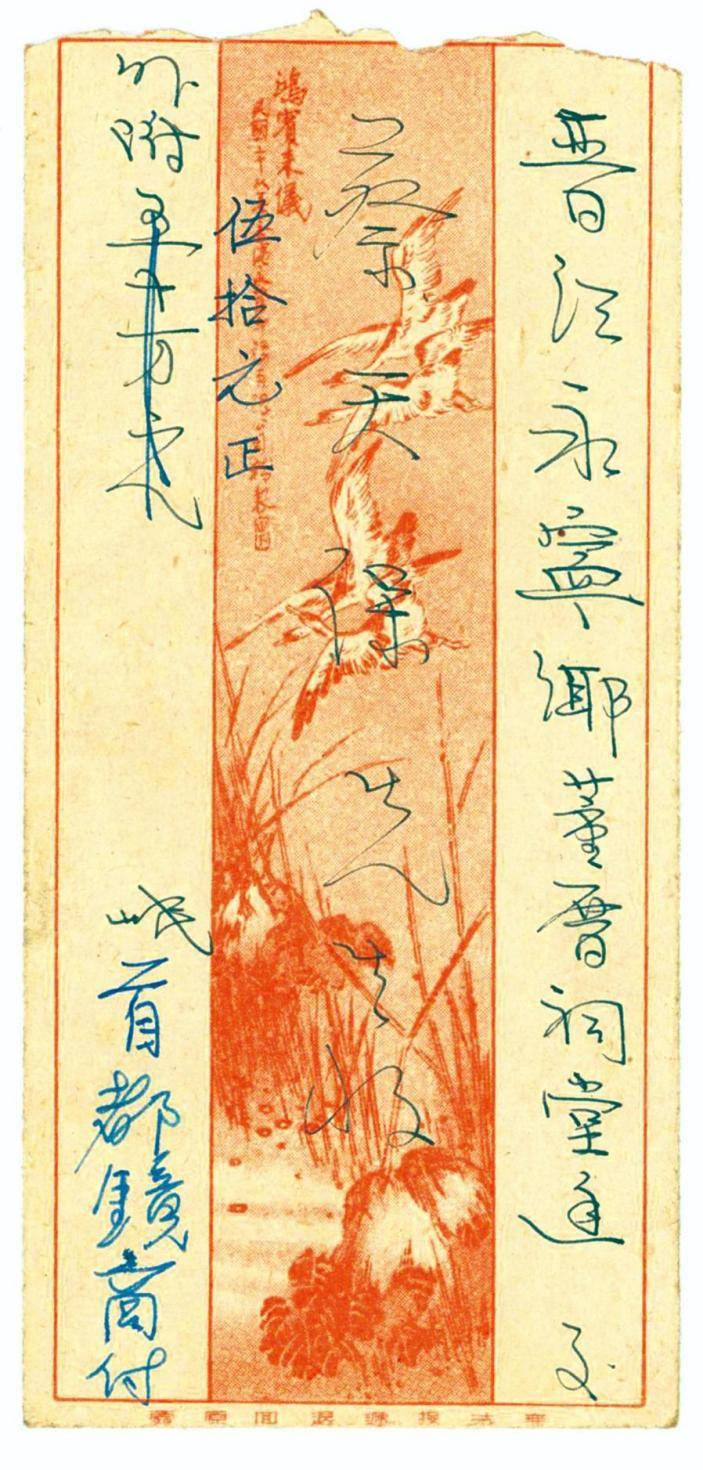
In modern times, overseas Chinese traveled across the ocean to make a living, and sent their hard-earned earnings back to their homeland along with letters from home, forming the earliest cross-border remittance form in China.
Qiaopi, also known as “Bank Letter”, is a unique carrier of credit and money for the Chinese. It has been included in UNESCO’s “Memory of the World Register” and carries the century-old cross-border capital needs of overseas Chinese to send money and express their thoughts across the sea. Bank of China has always been the core support of this cross-sea exchange route.
During the War of Resistance Against Japan, overseas Chinese in Southeast Asia relied on overseas remittances to support the motherland’s material procurement. Private credit bureaus closed down one after another and handling fees skyrocketed. Bank of China has established branches in Fujian and Guangdong to collect remittances at low prices and process remittances in full regardless of distance. The relevant responsibilities were recorded in “Memoirs of Overseas Chinese” by Tan Kah Kee. In order to break through the overseas policy blockade, branches in various places have used exclusive business names to protect the flow of remittances. Remittances ranging from small amounts to 5 yuan and large amounts of tens of thousands of Hong Kong dollars continue to support the livelihood of overseas Chinese family members and also provide critical funds for national salvation.
In times of peace, all private overseas overseas Chinese approval bureaus across the country were merged into the Bank of China, and the remittance payment work was fully undertaken by the Bank of China. In the early years, staff members rode bikes and sailed boats through the countryside, delivering remittances door-to-door regardless of weather conditions, building trust among overseas Chinese at home and abroad. Bank of China also donated a large number of original historical materials on overseas Chinese batches to the Fuqing Overseas Chinese Hometown Museum to preserve exclusive cross-border financial memories.
Over the past century, Bank of China has completely taken over the overseas Chinese batch service line and continued to promote the iterative upgrade of cross-border remittances: from manual delivery of overseas Chinese batches, telegraph remittances, to global payment networks, BOC has been deeply involved in every round of industry technological changes.
Accounts arrive in minutes, and the entire process is visible
Relying on BOC’s global cross-border financial network and intelligent clearing technology, “BOC Instant Remittance” comprehensively upgrades the cross-border remittance service experience:
First of all, the payment is received within minutes.In the past, cross-border remittances usually took several working days, and the cycle was even longer during holidays. “BOC Instant Remittance” compresses the arrival time to minutes. The first China-U.S. transaction only takes tens of seconds, redefining the speed of cross-border remittances.
Second, the progress can be checked.After the remittance is sent, the customer can track the progress of the transaction processing in real time through the mobile bank, from the remittance, the transfer to the account, each node is visualized throughout the process, and the status of the funds is clear at a glance.
Third, fees are transparent.In cross-border remittances, there are often differences between the amount remitted and the actual amount received, and the fee deductions in the intermediate links are not transparent to the remitter. “BOC Instant Remittance” realizes full payment without process deductions.
Fourth, 24/7 without interruption.In the past, cross-border remittances were restricted by bank working days and could not be initiated or received on weekends and holidays. “BOC Instant Remittance” can be initiated at any time, 7×24 hours, and is not restricted by working days.
Fifth, support the rapid recording of overseas remittances in RMB.Supporting accounts in RMB provides remitters with more currency choices and also expands new channels for the use of RMB in cross-border payment scenarios.
From first transaction to global presence
The implementation of the first real-time personal cross-border remittance transaction between China and the United States marks the transition of “BOC Instant Remittance” from technical verification to practical application.
“BOC Instant Remittance” targets a wide range of customers, covering overseas students, overseas Chinese, domestic families with overseas children, cross-border e-commerce practitioners and overseas workers. This customer group is large in scale and has high demand for cross-border remittances. It has high requirements for payment speed, fee transparency and operational convenience.
Of more strategic significance is the RMB entry function. By providing RMB account entry services, “BOC Instant Remittance” drives more foreign banks to access RMB remittance channels and promotes the depth of use of RMB in cross-border payment scenarios. It not only achieves product-level innovation, but also assists the process of RMB internationalization.
From the letter home soaked in sweat and longing in the overseas Chinese batch to today’s cross-border remittances initiated with one click on mobile banking and arriving in minutes, Bank of China’s original intention of connecting domestic and overseas Chinese and serving overseas Chinese remains unchanged.
The full launch of “BOC Instant Exchange” is just the starting point for a new round of changes.
Related reading
A reduction in holdings revealed the market’s deep anxiety about Haidilao
Text丨Wenlin On September 9, Haidilao fell more than 12% during the session and closed down 9.14%. Its market value evaporated by nearly HK$5.8 billion in one day. Since then, the stock price has been falling. If we count from the closing price of HK$11.38 on September…

Can the “height-limited” Taiyi save Nezha?
Zebra Production Fan Jian The mythical story of Taiyi Zhenren using lotus flowers to reshape Nezha's body is being played out in real shopping malls. Last week, news came out that Taiyi Shenglian invested 3 billion yuan to reorganize Nezha Automobile, and the market enthusiasm has…
Luo Yonghao complained about Mr. Savage, he kicked the cotton this time
"I tried it at the airport. The famous Mr. Savage is very average. Considering the price, it can even be said to be unpalatable." On the afternoon of September 12, Luo Yonghao posted another Weibo post criticizing a catering brand, which attracted the attention of the…