A few days ago, Luo Yonghao criticized Mr. Savage’s ice cream on Weibo for being unpalatable, triggering a wave of heated discussions.
While complaining, Luo Yonghao said “I miss Zhong Xuegao” for no reason. At that time, most people thought it was just a prank. Unexpectedly, a few days later, Zhong Xuegao was really “resurrected”.
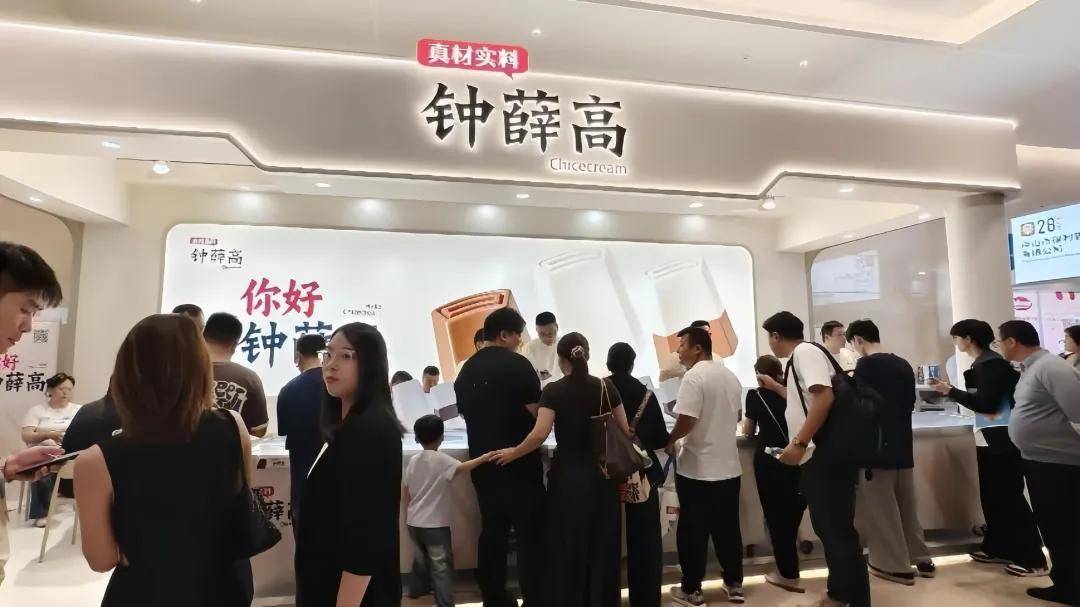
On September 16, at the 28th China Ice Cream Expo, Zhong Xuegao made his first public appearance after changing ownership.
It’s still the iconic tile-shaped ice cream, and it still has the classic flavors of light milk, velvet cocoa, and semi-smooth chocolate. Officially, the formula and ingredients are basically the same as the old version, but the numbers on the price tag have changed beyond recognition.
Light Milk is 6.9 yuan a bottle, Velvet Cocoa and Half-and-Half Qiao are 7.9 yuan each. Compared with the peak terminal price of 13 to 20 yuan, they are almost halved.
Hermès, once the ice cream world, has been resurrected in this way.
1. 雪糕刺客
When Zhong Xuegao was born in 2018, the entire ice cream industry was stunned.
Before this, the price ceiling of domestic ice cream basically stopped at 5 yuan, and the foreign brand Menglong was considered high-end, which was about 8 yuan. Zhong Xuegao directly raised the price to more than ten or twenty yuan, and also launched “Ecuador Pink Diamond” for 66 yuan a piece. Twenty thousand pieces were sold out within 15 hours, and he became a god in one battle.
That was the craziest era of new consumption in China. Traffic dividends are surging, and everyone loves to hear stories about consumption upgrades. As long as you have a good concept, a good look, and a good seeding, you can sell products that cost a few yuan at a premium several times over.
Zhong Xuegao took this gameplay to the extreme.
The Chinese-style tile shape builds recognition, the “without a drop of water” marketing creates a sense of quality, tens of thousands of notes are published in Xiaohongshu, and the stars in the live broadcast room bring goods, and a piece of ice cream has become a social currency in the hands of young people.
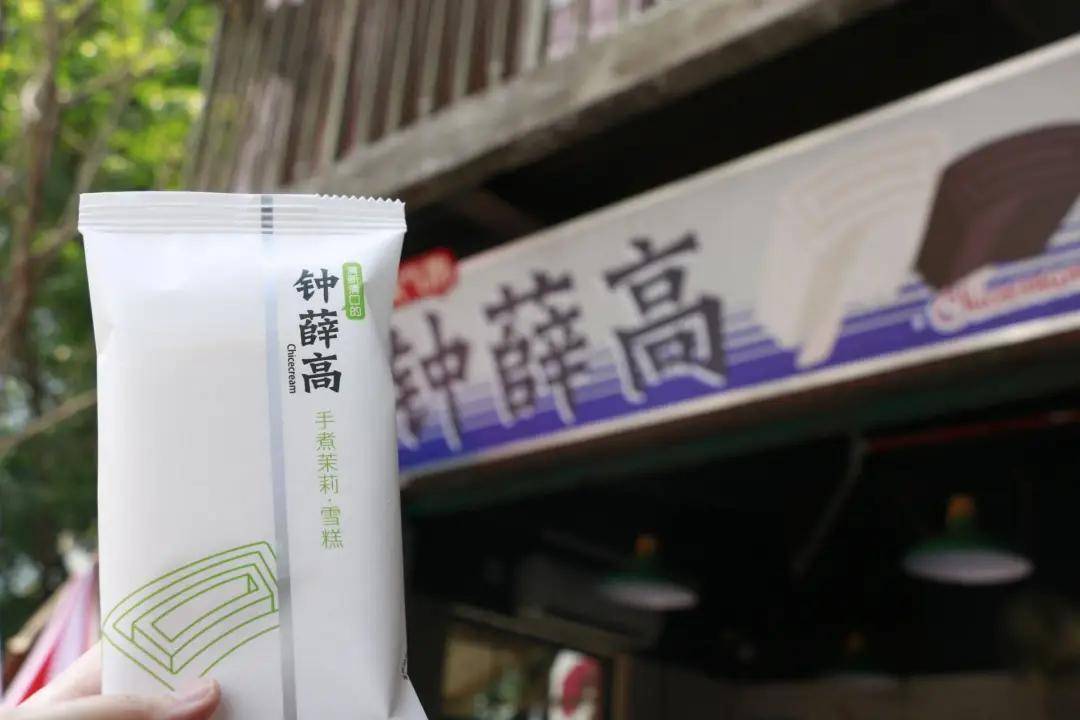
2021 is Zhong Xuegao’s peak, with annual sales exceeding 1 billion yuan and a valuation of 4 billion yuan. It was just a flash in the pan, and the tide receded soon after.
In the summer of 2022, complaints about the “Ice Cream Assassin” broke out across the Internet. Immediately afterwards, netizens released a test video of “the ice cream does not melt at room temperature of 31°C for one hour”, pushing Zhong Xuegao to the forefront of public opinion.
People suddenly realized that if I spend more than ten yuan to buy an ice cream, are I buying milk and cocoa, or am I buying overwhelming marketing?
Once the gap is opened in doubt, the bubble will burst faster than ice cream.
The plot then took a turn for the worse. Sales plummeted. Suppliers came to collect debts. Comments from employees asking for wages filled the official account. Lin Sheng was included in the list of dishonest persons and had to sell sweet potatoes in the live broadcast room to pay off his debts.
A brand that relied on marketing eventually died in the backlash of marketing.
In 2025, Zhong Xuegao Food (Shanghai) Co., Ltd. officially entered bankruptcy liquidation. A total of 508 intangible assets including 492 trademarks and 8 patents were packaged and auctioned, with the final transaction price of 21.1 million yuan.
2. 死而復生
After reviewing the incident, some people blamed Zhong Xuegao’s collapse on the public opinion of the “Ice Cream Assassin” and on the ice cream that “didn’t melt”.
In fact, it is not the case. It has been locked in its own pricing logic from the beginning.
A piece of ice cream with a factory price of only two or three yuan can be sold for more than ten yuan by relying on marketing packaging and channel premiums. Essentially, it earns information gap and emotional tax. When the traffic dividend reaches its peak, such a price system will be broken at the first touch.
The new team that took over Zhong Xuegao obviously understood this.
The current operating entity is Zhong Xuegao Brand Management (Shanghai) Co., Ltd. The actual controller Wang Yaqing holds 60% of the shares, and the remaining 40% of the shares come from the parent company of the quick-frozen food brand Royal Tiger. Chen Dacheng, who serves as CEO, is a food review blogger with millions of fans on the Internet. He has been in supermarkets and channels all year round, and he knows best what people are willing to pay for.
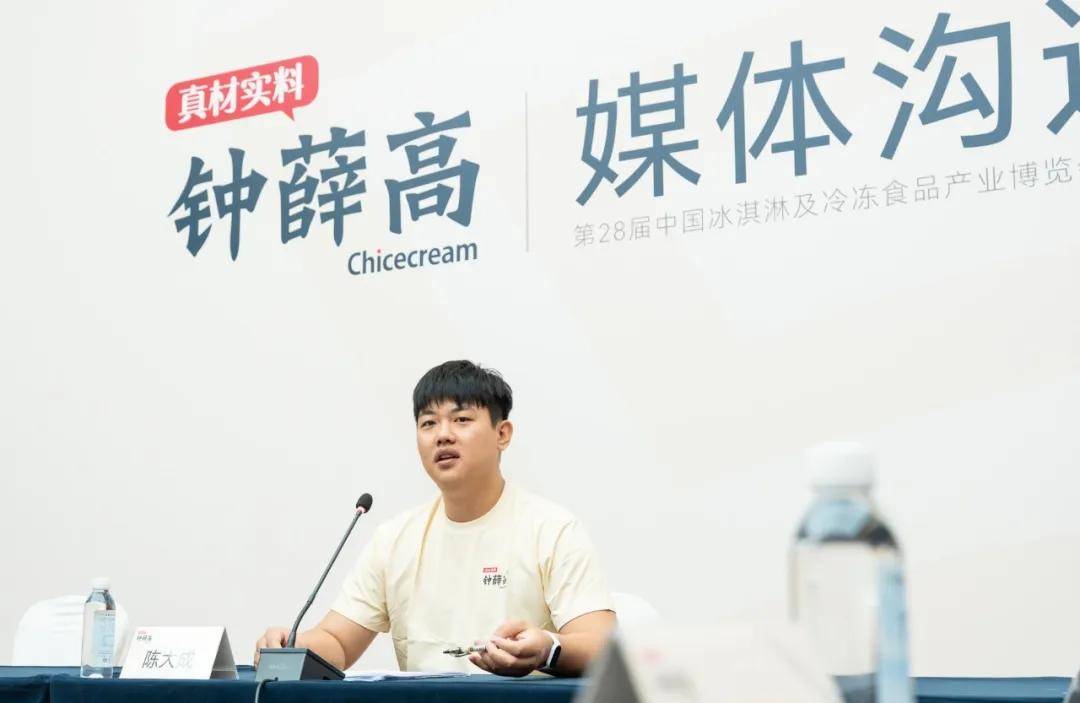
The first thing these people in circulation and industry did after taking over was to drag Zhong Xuegao back to the ground from the clouds – the formula and ingredients remained unchanged, but the price was cut in half.
Many people think that the price of raw materials has dropped, but this is not the case. Officials themselves admit that the ex-factory prices of the first batch of products are similar to those in the past. Then why can the retail price drop from 16 yuan to 7.9 yuan?
At that time, most of Zhong Xuegao’s retail price was marketing fees, channel entrance fees and profits from dealers. If you want to maintain a high-end personality, you have to spend money on planting grass and traffic; if you want to enter the core freezer of a convenience store, you have to pay high barcode fees and display fees; if you want dealers to be willing to promote it, you have to leave enough room for price differences.
These costs will eventually be spread to each ice cream, and consumers will pay for it.
Now the new team is taking a completely different path: production is outsourced, and there is no need to build a factory of your own and heavy capital investment; channels are borrowed from Royal Tiger’s ready-made network, starting with online and snack mass-selling pilots, eliminating the need to increase prices at all levels.
3. 新的算盤
The new team’s calculations go far beyond just reducing prices.
After the resurrection of Zhong Xuegao, why is the price stuck in the range of 6-8 yuan?
At the bottom, 3-5 yuan is the red ocean of Yili, Mengniu, and Qiaolezi. The competition is channel depth and scale effect, and new players cannot squeeze in; at the top, the position above 10 yuan is the position of Magnum and Haagen-Dazs. It is also the place where Zhong Xuegao overturned. Consumer trust has not been restored, and it is a dead end to go back.
6-8 yuan is exactly the price range with the gentlest competition and fastest growth. It is stuck between traditional ice cream and high-end ice cream. It is more advanced than ordinary ice cream, but not as assassin-like. Consumers have a low threshold for decision-making. They can just take it and leave without worrying about it.
The more important trump card is channels.
Royal Tiger started out as a quick-frozen food company, with omni-channel terminal retail sales exceeding 4 billion yuan in 2025. Its channel network covers snack wholesalers, supermarkets, community group purchases, and catering B-sides, and it has penetrated deeply into the sinking market. Snack discount stores such as Zhao Yiming and Snack Busy are the fastest growing channels for cold drinks in recent years. They have a natural demand for cost-effective ice cream worth 6-8 yuan.
In the past, Zhong Xuegao had to spend a lot of money on entry fees and freezer fees to sell it in convenience stores. Now it is directly linked to Royal Tiger’s channel system, which is equivalent to having ready-made shelves at birth. Production still relies on the original foundry, which is an asset-light operation. There is no need to build a factory or heavy investment in assets, keeping costs to a minimum.
To put it bluntly, Xinzhong Xuegao is taking the monetization route of “well-known IP + affordable channels”.
4. 寫在最後
Zhong Xuegao’s resurrection is like a mirror, reflecting the changes in new consumption in recent years.
In the last cycle, we believed that consumption upgrading meant more products sold became more expensive. Brands compete to see who has a higher price tag, whose story is more touching, and whose marketing is more out-of-the-box.
In this cycle, we return to common sense, essence, and cost-effectiveness. Bubbles burst one by one, stories fail one by one, and those who survive in the end are the players who can make good products, keep prices level, and develop channels thoroughly.
From a valuation of 4 billion to an auction of 21.1 million, from 16 yuan a piece to 6.9 yuan, Zhong Xuegao’s fall and rebirth are a footnote to an era.
Soon, we may be able to buy Zhong Xuegao for 6.9 yuan in the snack shop downstairs. I wonder if those who picked it up at that time would remember the curious and painful feeling they felt when they picked it up in the freezer of a convenience store a few years ago.